The Invulnerable Hero*
January 28, 2021·Money
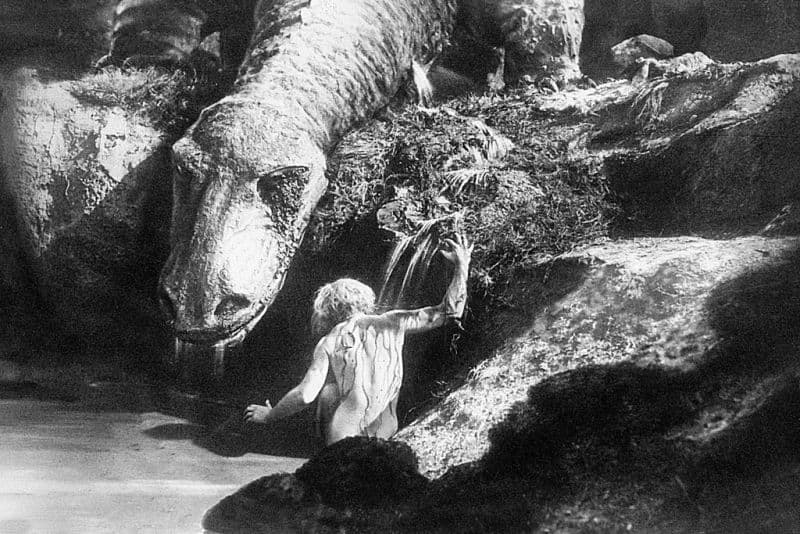
Siegfried bathes in dragon's blood, from Fritz Lang's Die Nibelungen (1924)
The Invulnerable Hero* is among our most treasured and recurring tropes.
It is the core feature of the great German epic, the Nibelungenlied. You probably know it better as the story of Siegfried from Wagner's treatment of the story in his famed Ring Cycle. Siegfried slays a dragon and bathes in its blood, that is, everywhere except for the spot on his back covered by a drifting linden leaf. He thus becomes invulnerable to harm except in this very spot.
To those of you more familiar with the Greek epics, you will no doubt see the parallels with the story of Achilles. Thetis takes an infant Achilles to the River Styx and dips him into its waters. He thus becomes invulnerable at every spot but the one covered by the fingers by which his mother held him beneath the Styx: his ankle.
For the more cultured among us, we have our Superman story. Our invulnerable hero with practically every possible advantage and a weakness to one substance that, like the Achilles heel, is so iconic an expression of the trope that it is now a euphemism for a singular weakness or point of failure. Kryptonite. And no, nerds and/or Ben, please do not email me your pedantic notes on red sun radiation, etc.
Still, there's a funny thing about Invulnerable Hero* stories. Though we know the hero is all but invulnerable, and though we know that the only real conflict in our story is one which might threaten their single point of vulnerability, the stories are rarely about the vulnerability itself. The stories are about their great battles, their great triumphs and the roles they play in the other stories of their time. Stories which pose them practically no threat.
And even though those stories aren't the real story, they still matter.
I know that we all want to believe that the story of GameStop is really about regular people sticking it to institutions that have done the same thing to others for years. That a revolution has taken place.
I could give you my suspicions that most of the volume and capital that have driven the short squeezes have come not from Reddit or other retail investors but from institutions (read: other hedge funds) who quickly devised strategies to predict where the energy produced by these groups would be directed next. But they would be only suspicions. Pretty strong ones, mind, but still suspicions all the same.
I also think there's a certain misguidedness to so much of what has taken place, driven by the belief that it's short-sellers who are the ones who most aggressively manipulate the system and do harm to the average investor. I can think of many cases where this is specifically true, and I can think of many cases where this is categorically false, cases in which this group of investors have been among the only truth-tellers left, opposed by the same financial media that patronizes retail investors today. Lazy fund-of-fund diligence analysts, hubris-and-implicit-debt-laden macro funds and 2-and-20 long/short funds minting decamillionaires by delivering 30% net exposure to the S&P and the occasional branded Patagonia vest have each extracted far more real value from the average investor and citizen.
But leave both of those things aside. Because it's still a good story. It's a story I think people will remember. It's a story that still matters, even if it isn't 100% true and even if its target was maybe a bit off-the-mark.
But it also isn't the real story. It isn't the Invulnerable Hero* story.
The real story is the one that lies underneath: it is the story of the source of cascading events in markets, of short squeezes and events in which those squeezes lead to large de-grossing events in which funds rapidly reduce their exposure and cause the kind of broader market events that do have real-world effects. It is the story of the heel of Achilles, the shoulder of Siegfried, the kryptonite of Superman.
It is the story of leverage.
It is the story of the gross exposure which we have collectively decided is the birthright of these institutions.
As they have many times before, regulators, financial media and financial institutions are responding to make sure that this Achilles heel doesn't lead to the kind of wildfire event that it very well could. As they have many times before, they are doing so not by addressing the Achilles Heel of leverage and excessive gross exposure, but by seeking to prevent whatever proximate cause threatens to expose that weakness. Last year it meant our government providing a bid for assets that had none. In this case, that means our government and institutions doing what they can to prevent the establishment of new positions by retail investors.
When the dust settles in the next couple days, you'll get the usual laughing "This time it's different...not!" thinkpieces from Very Respectable Investors, and they'll be mostly right. Short squeezes aren't new. De-grossing events aren't new. Goofy run-ups happen all the time. But there is a new common knowledge that applies to a much broader audience.
The place where Achilles was held when he was dipped into the River Styx is now common knowledge. The spot covered by the linden leaf on Siegfried's back is now common knowledge. Superman's home planet is now common knowledge.
Soon, the fact that hedge funds have long been and are now even more actively scraping, watching, predicting and pouncing on public, pseudo-private and private social networks will become common knowledge. Their realization that they can free-ride on asymmetric, illiquidity-driven trades that don't create the same regulatory risk as their own public agitation and collusion might will become common knowledge.
That an entire industry is vulnerable to and will itself join in cannibalistically with this kind of coordinated attack will soon become common knowledge.
I suspect that the gatekeepers and regulators will have to face the choice: do they want free and fair markets for the pricing of capital in which everyone plays by the same rules, or do they want to protect the birthright of the hedge fund industry to run high levels of gross exposure and substantial explicit and implicit leverage that will continue to necessitate these impartial emergency restrictions and rescue packages?
We know what they've chosen before.
Maybe this isn't the revolution some were hoping it would be. But it might be a policy inflection point. There might be an opportunity to build a movement around fairness, truly free markets and the rule of law.
Let's tell those stories.
Comments
Good note Rusty. Narratives inside of narratives inside of narratives on this one, hard to untangle but fascinating. It was fun that ET via Donnelly’s guest post last week was ahead of the crowd on this (not unusual for ET obviously), although I still feel his early take had a lot of gatekeeper narrative to it (kept seeing other’s take home was around ‘the new gen of reddit degenerates’ narrative which I think is total BS). Your note much more fair imo, seems pretty straightforward to me to assume that this has not remotely been all retail and WSB and that cannibalistic institutions happy to join in, yet the low hanging fruit “Boo reddit degenerates” narrative will certainly be opportunistically taken advantage of by Boomers to dismiss and by the rule makers to change the rules, as is already happening.
I largely agreed with Radigan Carter’s take (highly recommend to ET audience which I expect may not be so fond of it from demographic standpoint) that Boomers et al are vulnerable to naively assuming that anyone who says ‘it is different this time’ is a young fool, while in reality from my middle age ‘stuck in the middle’ perspective the rules of the game a la The Long Now and resulting change in incentives (it is now rational to speculate before music stops), esp for younger people, are a pretty major structural change. And the tools and access have clearly evolved significantly (ET has discussed this much in the past also, perhaps more around fiat news than investing). So I’m with the young people that big changes are afoot and I scoff at anyone who’s dismissive of that. On the other hand the young degenerates think they’ve won something when in reality the rule-makers are like the FED and they will never run out of ammo (ET: Stalking Horse), as you said hardly the revolution some hope for.
Last my mind is already reeling when I take a small step back…In the last MONTH the following common knowledge events have occurred: 1. US citizens, at least white ones, can violently invade the centers of power and walk away (next time cover your faces fools), 2. US oligarchs will decide who gets to freely use the ubiquitous communication platforms they’ve built and who does not, 3. Digital ‘occupy’ type movements can accomplish much more than physical ones per effort expended, and 4. Financial institutions will simply BITFD any vestigial perception of free markets before they consider addressing root causes. Obviously these types of conclusions will not surprise ET readers but I think there is still a surprising and fundamental lack of mainstream awareness of much of the deeper currents going on here.
Wow, great comments, Rech. I’ll take a look for Radigan’s piece on this.
Note that through the pandemic, complex systems without leverage (internet, package delivery, for example) worked fine despite heavy stress and massive volumes. The financial system is uniquely unstable due to leverage.
And uniquely unwilling to grapple with that, no matter how many times it raises its head.
I sure hope we find out who was behind the decision that several online trading platforms made today to stop trading in certain stocks all within minutes of each other , just like the major networks all deciding at the same time to switch away from the Presidents news conference the day after the election.
Just like all the Social Media company’s deciding that of all the thousands of news articles in existence that day - the New York Post article needed to banned. Again at the exact same time!
There is nothing free and fair about any of this.
Rusty - Thanks. Quite insightful, as always. I trust you’ll push any data that you find supporting your “suspicions” to us.
During a media appearance today, I got a spike in responses on social media for suggesting that brokers have the free market right to protect their balance sheet. 2:1 against. With a clear Retail Bros vs. Boomers flavor. So I’d love some detail on your closing thought.
Fairness + free markets + rule of law: Do you have quick thoughts on what a reasonable response to the recent frenzy would include?
Thomas Peterffy was interviewed on Bloomberg just prior to the close and threw out some interesting numbers. 3 million open option positions on GME, average contract value of $10,000. So, there are $30 billion worth of derivative bets on what was a sub $20 billion stock. This is how the short interest exceeds the float. And, one side has lost $30 billion (the shorts) and one side has made it. But, the shorts are being force liquidated as they no longer have account value. His concern (judge for ourselves his veracity) is that the clearinghouse integrity is in question and this can take down the brokerage firm when the client has no money to make good. His estimate is that IBKR has about 5% of the accounts with a position in GME and their system automatically liquidates as account values hit thresholds of no margin. He doubts all firms have their system. And, I just saw a headline that Robinhood is having to draw on credit lines. Once again, leverage is at play when things go this haywire.
BITFD
Good conversations starters and very good questions - let me suggest that we move the detail to the forums so that we can hear from more people than just me (ie - please start the thread!).
How about this for starters?
https://wallstreetonparade.com/2021/01/gamestop-shares-dark-pools-owned-by-goldman-sachs-jpmorgan-ubs-et-al-have-made-tens-of-thousands-of-trades/
Continue the discussion at the Epsilon Theory Forum...