The United States of Bed Bath & Beyond
May 16, 2023·Money
Download a PDF of The United States of Bed Bath & Beyond (paid subscribers only)
A grown man made a wager. He lost.
He made another wager. He lost again.
End of story.
The Sopranos (season 2, episode 10)
In season 2 of The Sopranos, Davey Scatino – owner of Ramsey Sports and Outdoors and degenerate gambler – loses $10,000 in a poker game run by one of Tony Soprano's associates. Davey, an old high school friend of Tony's, begs him to let him play in the higher stakes poker game, the Executive Poker Game, so he can win his money back. Tony advises against it, but eventually agrees, staking Davey with $50,000 for the game. Davey loses, of course, and now Tony Soprano owns him.
"You told me not to get into the game, why'd you let me do it?"
"Well, I knew you had this business here, Davey. It's my nature."
At which point Tony and his associates proceed to ‘bust-out' Davey's sporting goods store.
They buy high-priced items on store credit to resell for cash, max out the store's credit lines with suppliers, and generally loot the store. Ultimately Davey declares bankruptcy, is divorced by his wife, and moves to Nevada. The last we see of Ramsey Sports and Outdoors is a liquidator putting up a store closing sign.
Oh wait, that's not Ramsey Sports and Outdoors.
But of course it is.
The story of Bed Bath & Beyond is the story of grown men, weak men, making wagers that they lose over and over again.
The story of Bed Bath & Beyond is the story of grown men, rapacious men, whose nature is to bust-out the weak men as cruelly and certainly as possible, over and over again.
The story of Bed Bath & Beyond is our story, the story of the United States here in the fin de siecle of The Long Now, where our entire country has been busted out and stripped for parts by grown men, rapacious men, different from Tony Soprano only in that they plunder legally within a system of courts and laws and regulatory agencies.
The story of Bed Bath & Beyond is a story of loss and sadness.
The story of Bed Bath & Beyond is the story of what happens when Story ends, when the reality of the bust-out — crappy stores and crappy management and overwhelming debt — finally swamps the narratives of Stock Buybacks!TM and Turnaround!TM and Short Squeeze!TM.
And maybe a story of hope.
Hope how?
Hope that the reality of the American bust-out — crappy institutions and crappy leaders and overwhelming debt — will begin to swamp the narratives of Yay, Stock Market! and Yay, College! and Boo, MAGA! and Boo, Wokeism!.
Hope that the assignment of losses here at the end of an age will force us to call things by their proper names, to identify weakness as weakness and rapaciousness as rapaciousness and narrative as narrative. Hope that we will have the courage to reject them all. Hope that we will choose to be more clear-eyed and more full-hearted as we move forward with resolve to Make/Protect/Teach in the world beyond bust-out.
So here is the story of the weak and the rapacious and the narrative-driven. Here is the story of Bed Bath & Beyond. Not for shame or schadenfreude, but for hope.
There are at least three distinct phases of the Bed Bath & Beyond bust-out.
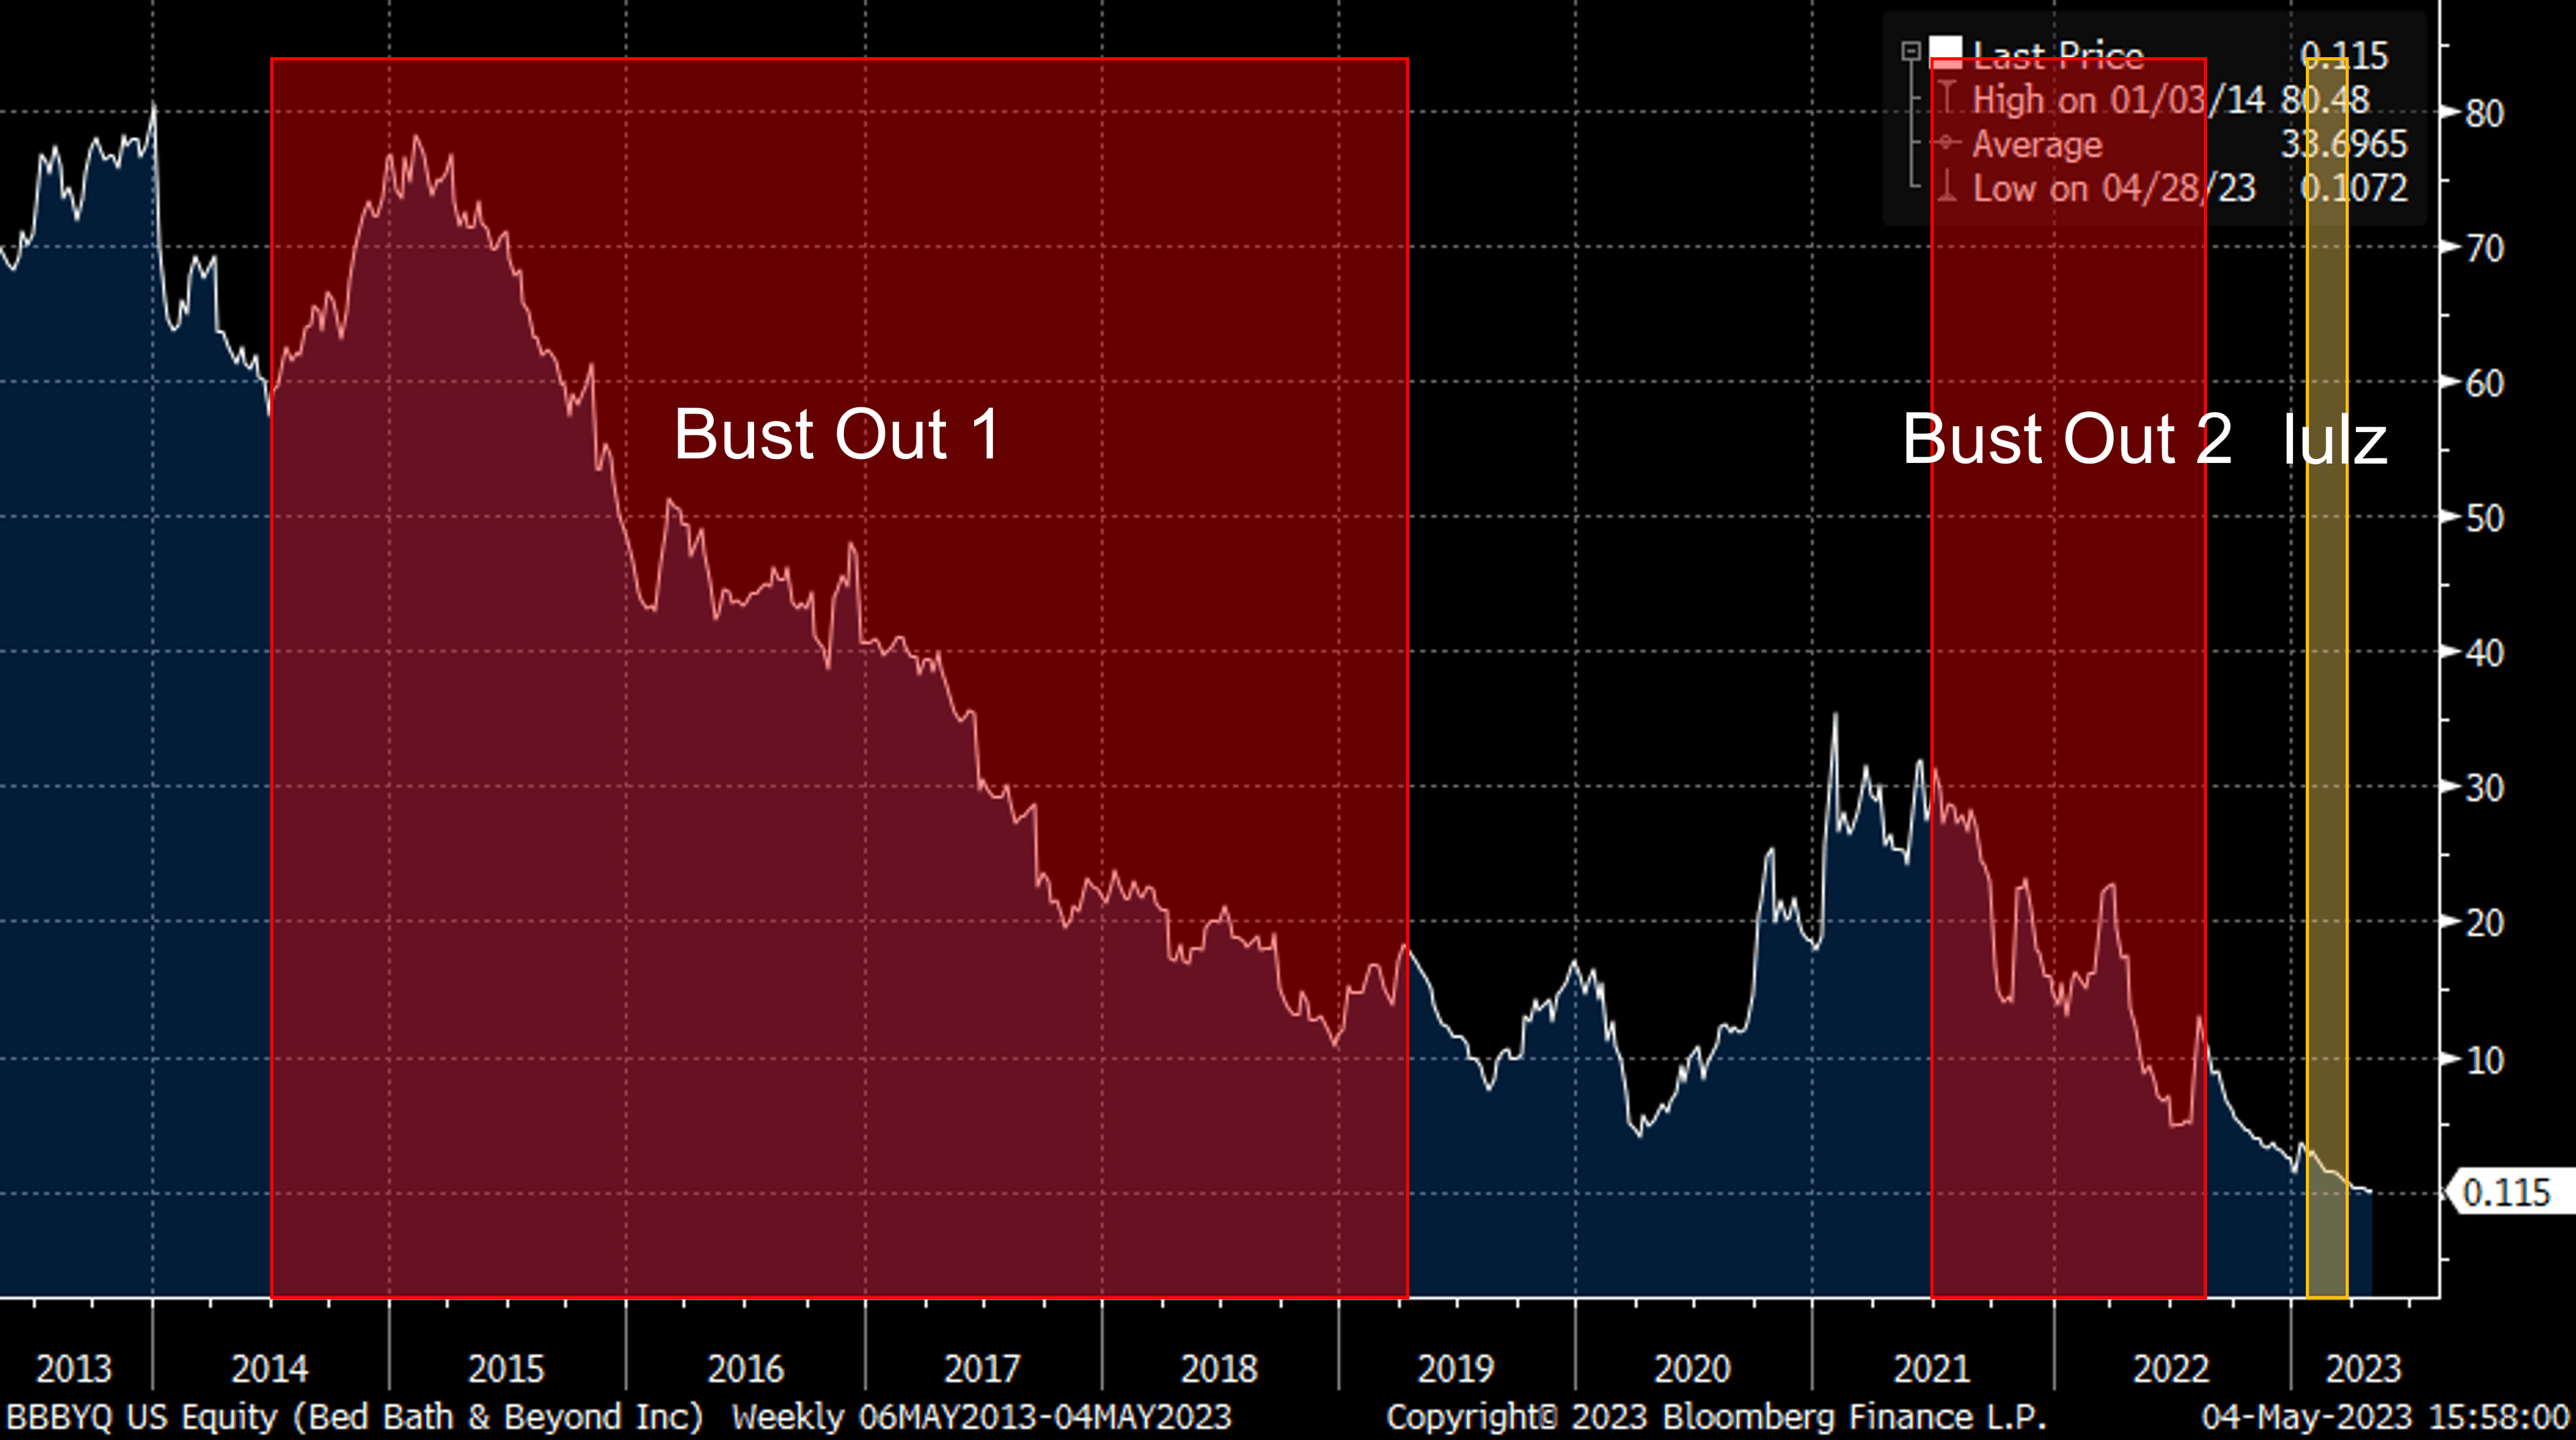
Bust Out 1 was orchestrated by the original founders and management of the company. This is where most of the money was sucked out of the company, and by the time the original founders and management were deposed in May 2019, the company was already dead.
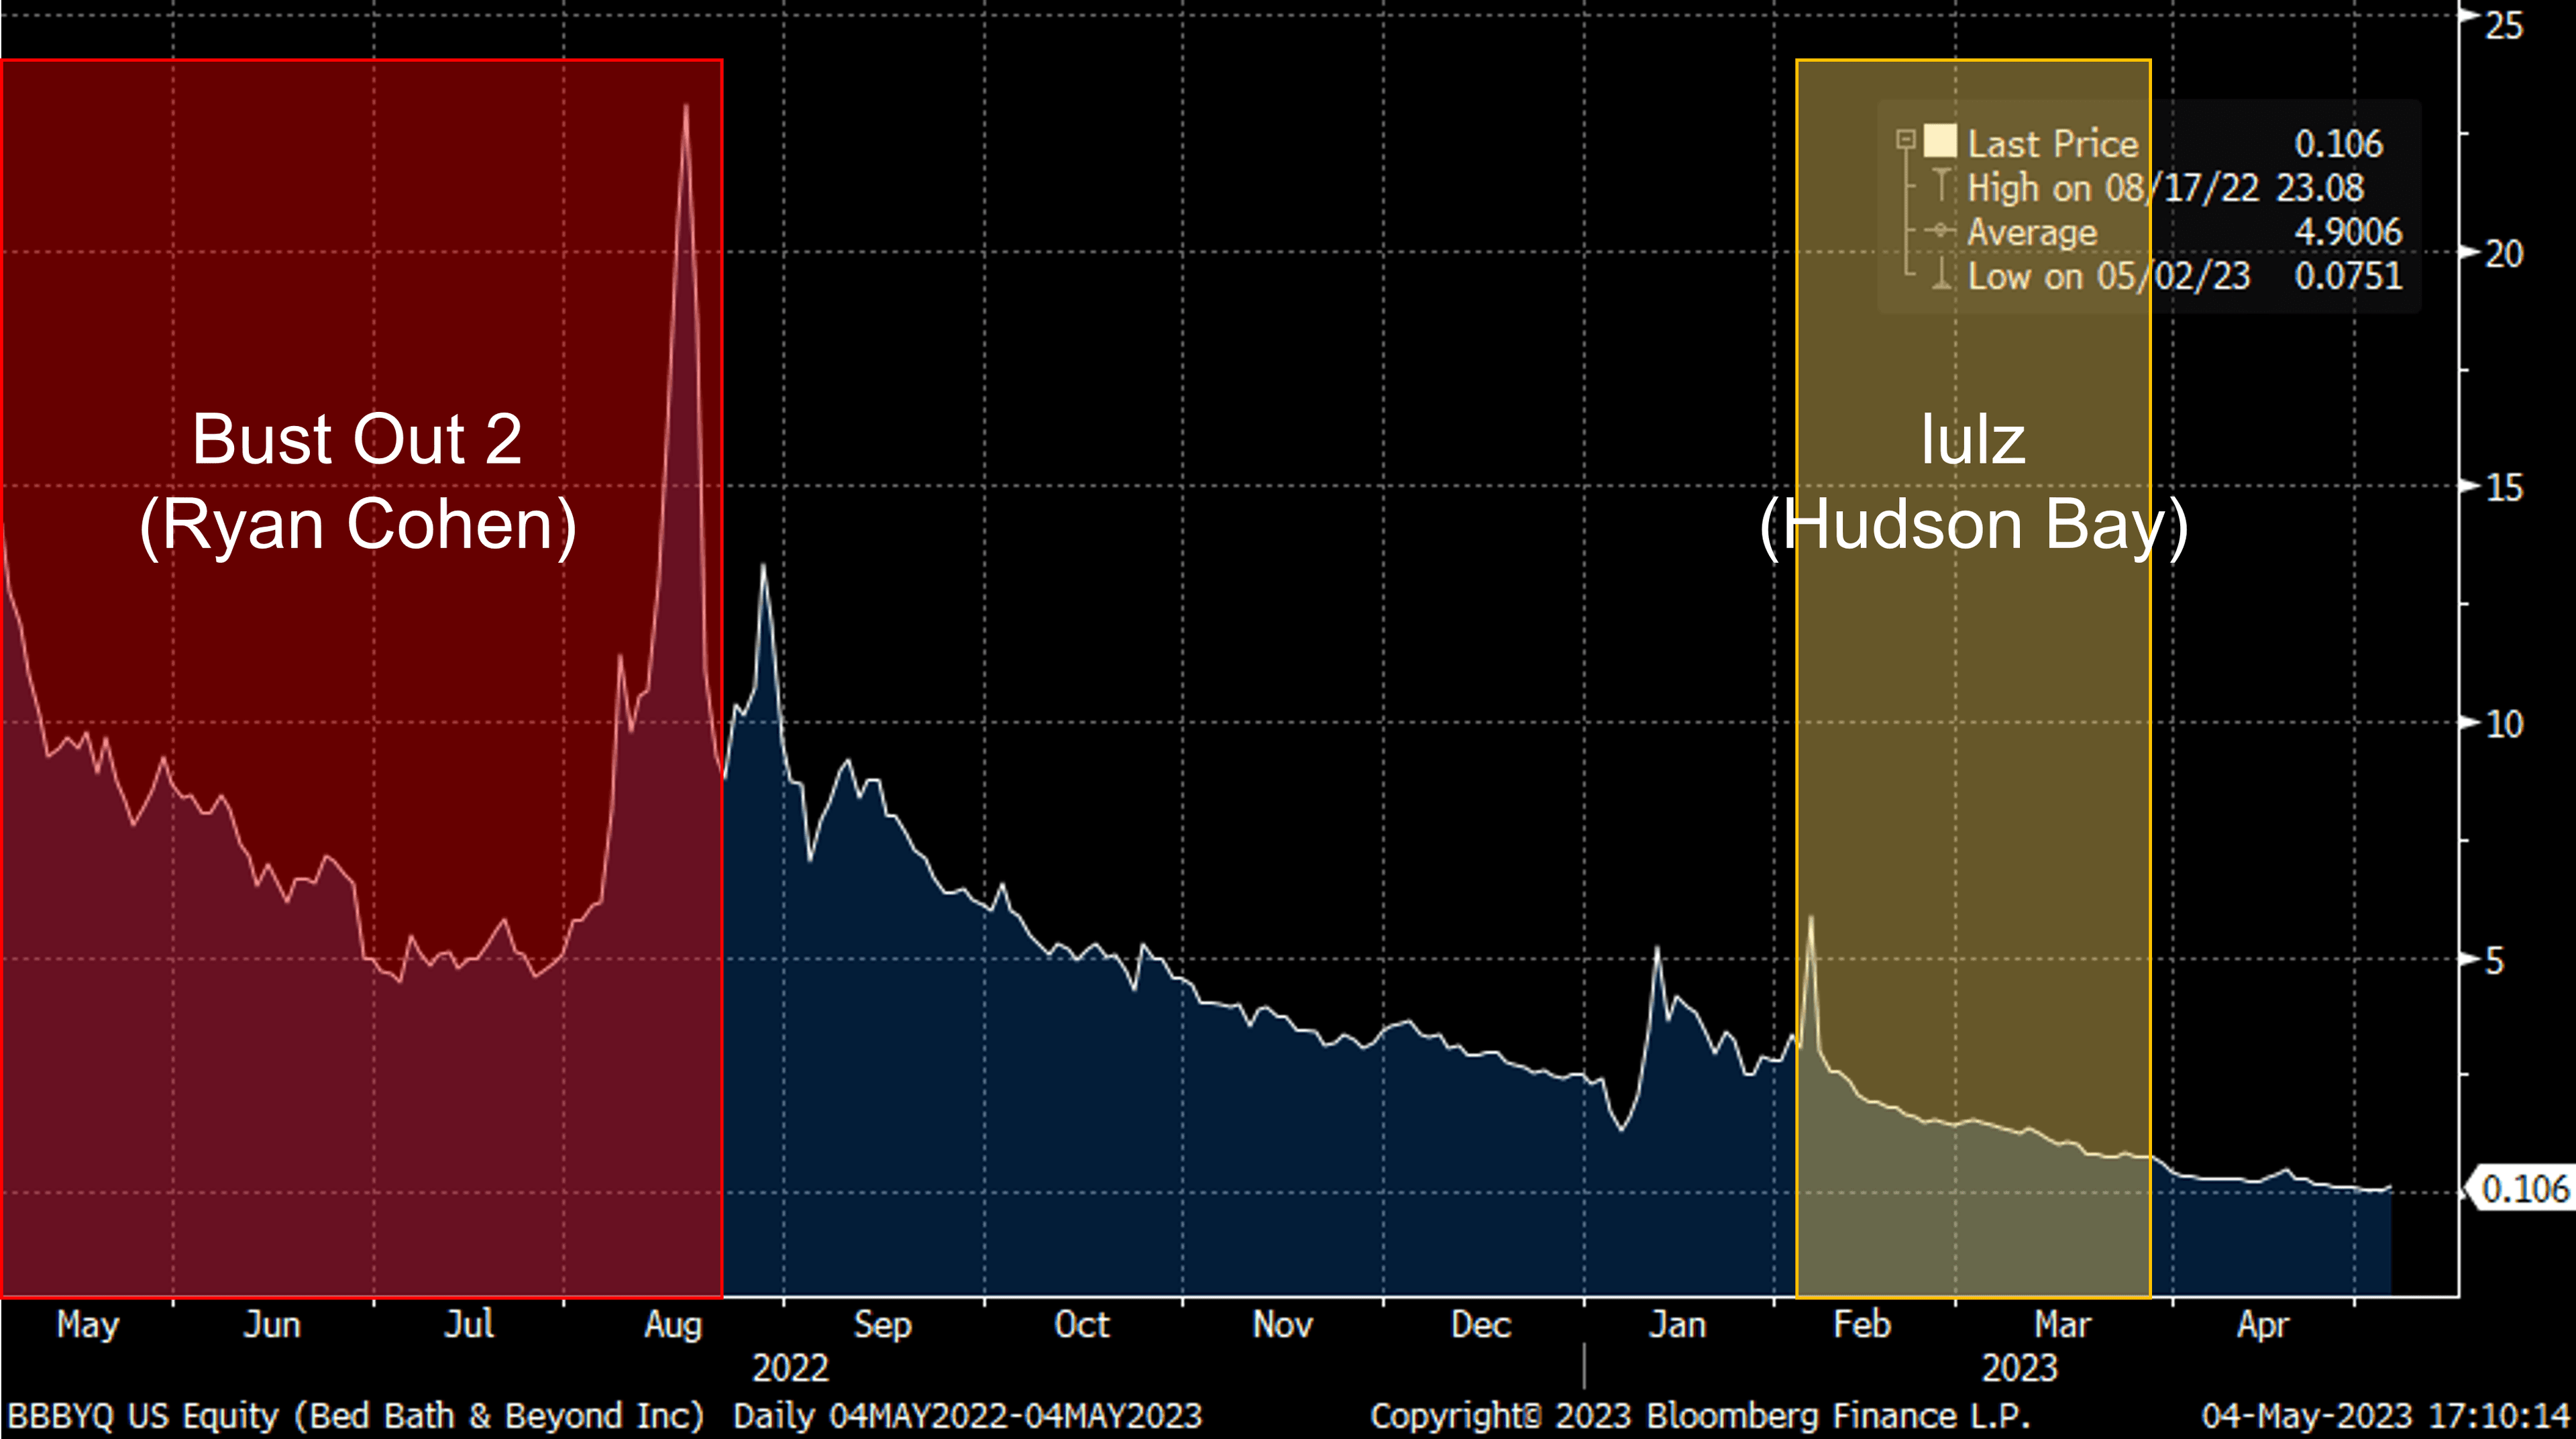
Bust Out 2 was orchestrated by the management team that replaced the Bust Out 1 team, together with an external investor, Ryan Cohen.
Bust Out 3 is so outrageous – a self-proclaimed functionally bankrupt company selling self-proclaimed worthless equity to Meme investors, degenerate gamblers all – that I just call it the lulz period.
Both Bust Out 2 and the lulz period were quite speedy looting operations, so I've zoomed in on the past 12 months to show the stock price moves more clearly. In particular, the exit spike for Ryan Cohen's Bust Out 2 sale was so fast that his exit price of $22+ per share doesn't even register on the long-term chart above!
In general, I think this is a common factor in all bust-out processes, whether of a company or a country, that the individual bust-out episodes become shorter, sharper and more ridiculous as there's less and less juice to squeeze out of the orange.
Now let's look at each of the bust-out periods in more detail.
Bust Out 1 (2014 – 2019)
We should start with the numbers before we tell the story.
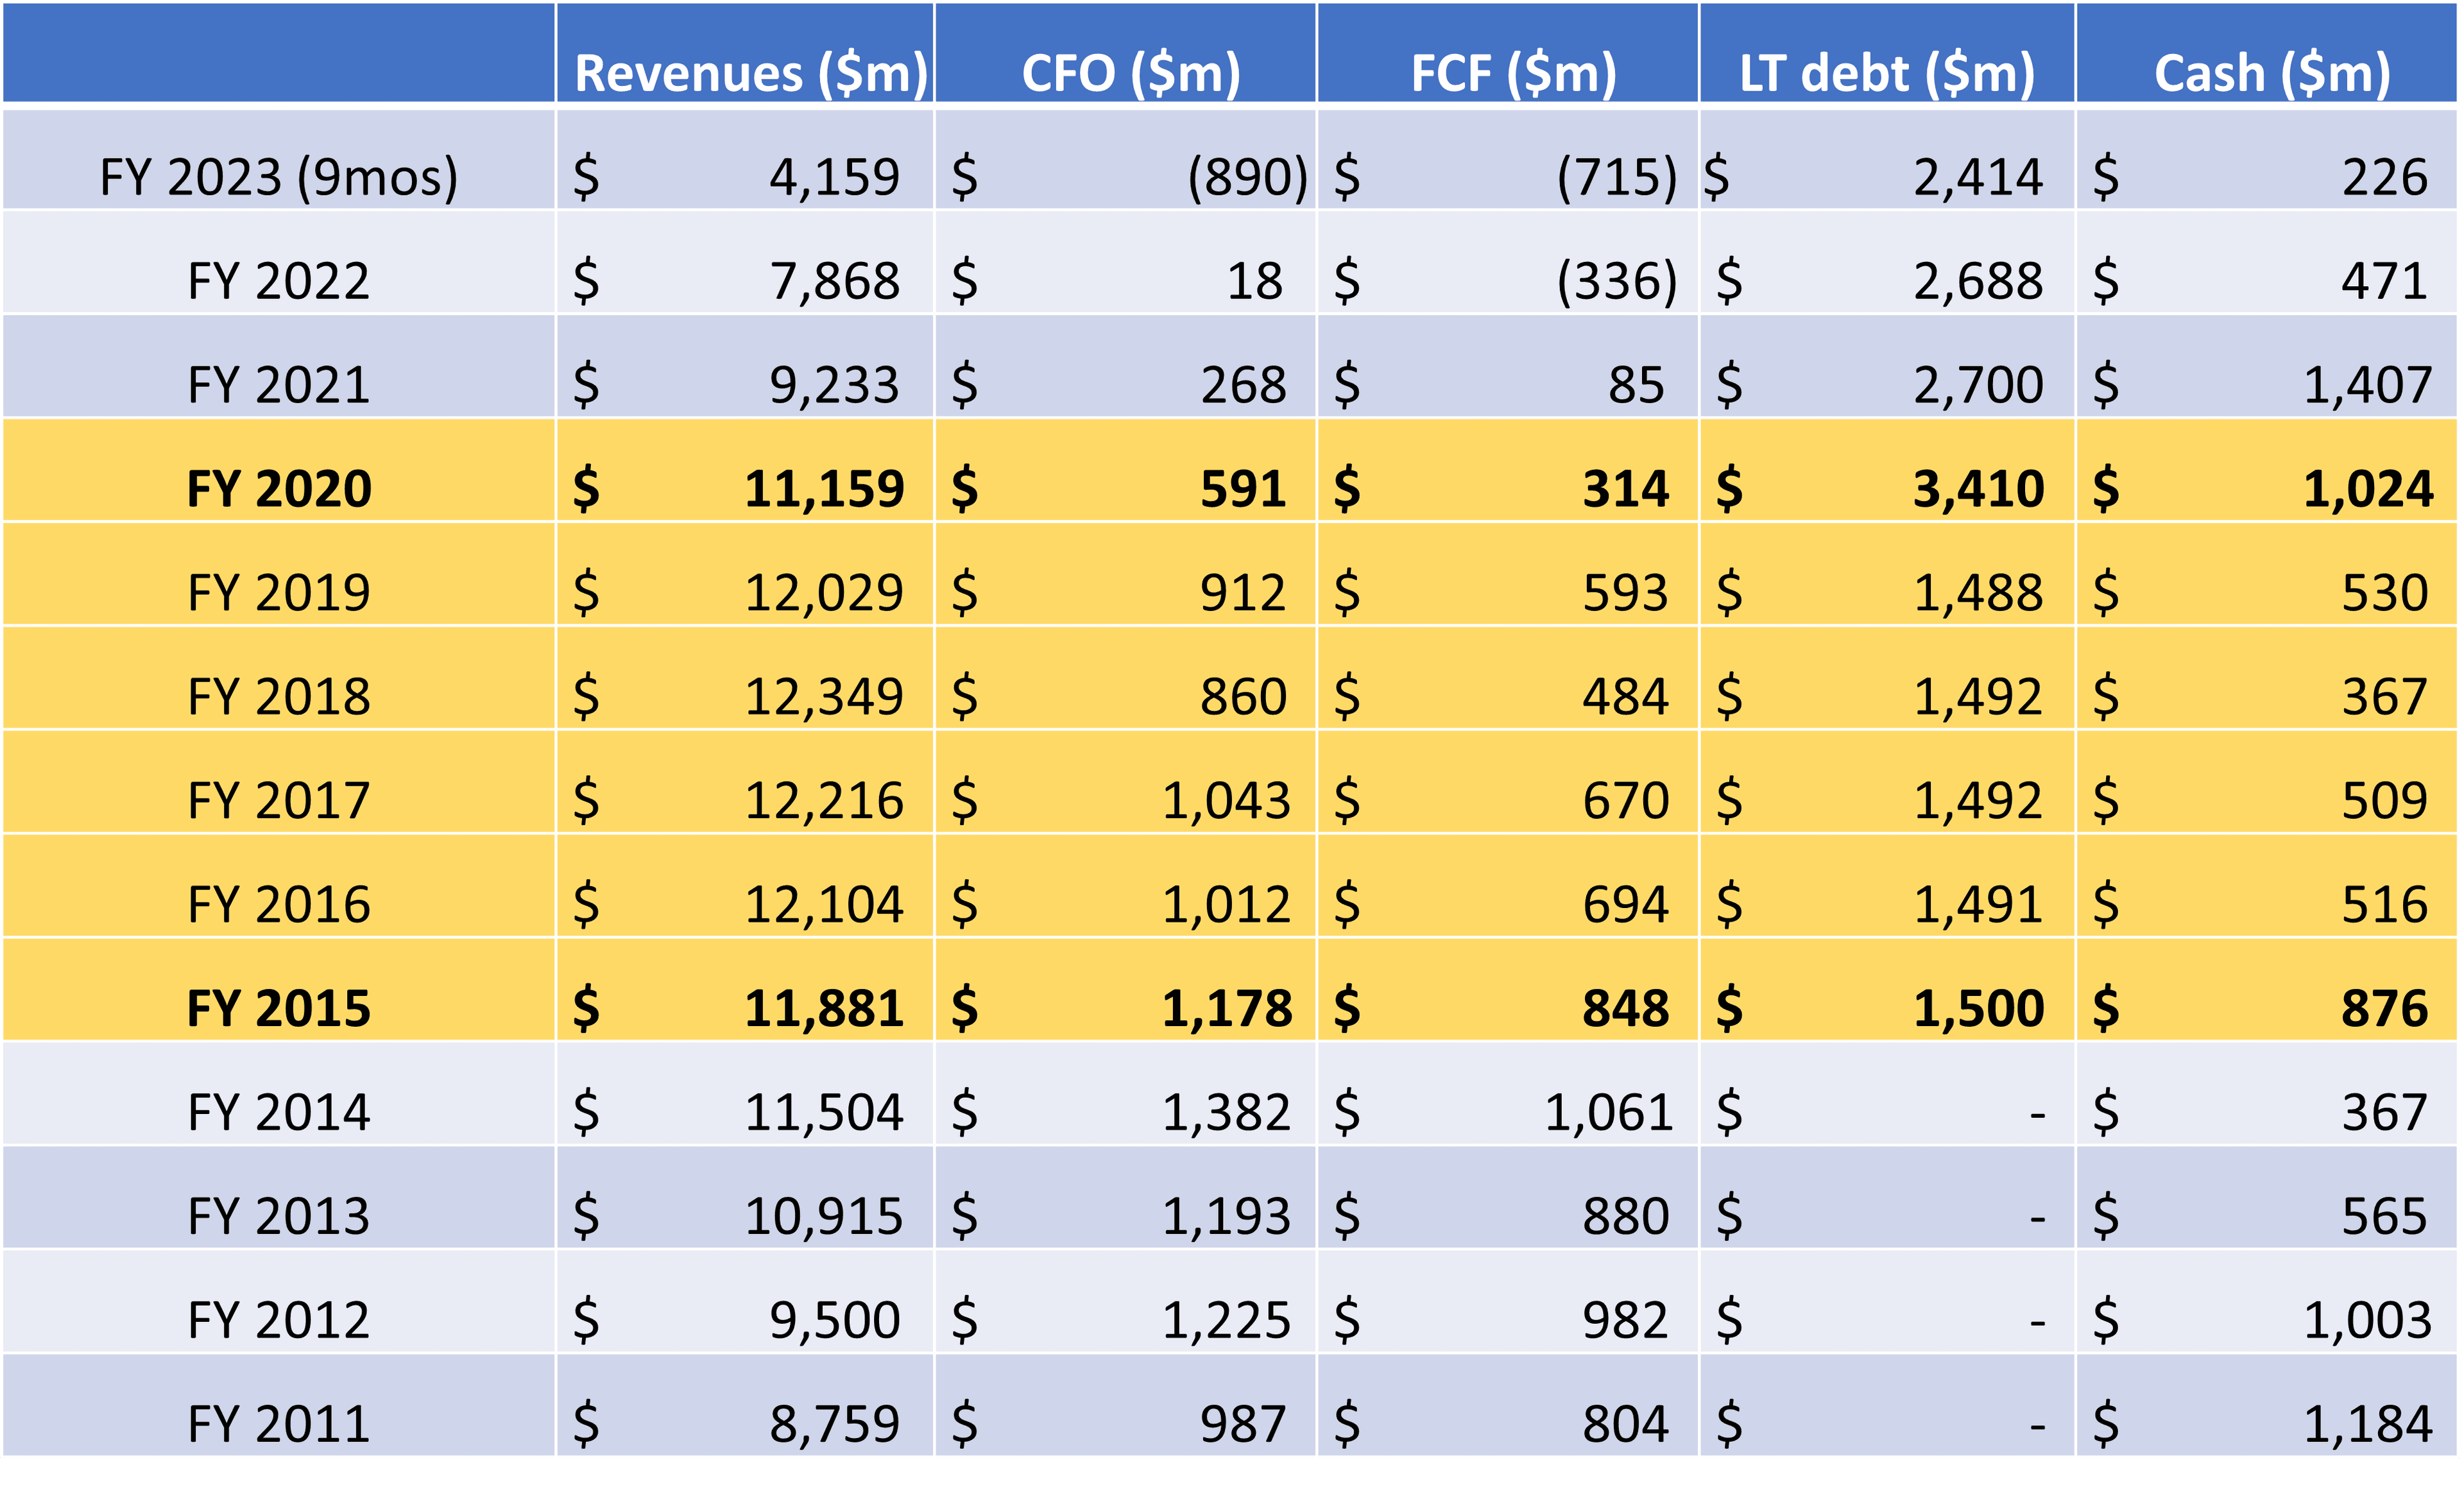
Bed Bath & Beyond financials (source: 10Ks, 10Qs, Bloomberg)
Like many retailers, Bed Bath & Beyond reports its annual financials on a February fiscal year, so that their results capture the full Christmas shopping season as the culmination of the business year. This can be a little confusing, because when the chart says, for example, FY 2022, that's actually only two months of 2022 and is mostly made up of 2021 results. Adding to the confusion, BBBY has delayed its FY 2023 annual filing, so I have to use 9 months of quarterly filings for the FY 2023 line, none of which occurred in 2023. So when I say things like "Bed Bath & Beyond died in 2019", I'm referring to the FY 2020 results.
Otherwise I think everything is pretty self-explanatory. CFO is cash from operations, essentially the profitability of your core, real-world business. FCF is free cash flow, the amount of money left over from CFO after you've satisfied the cash burden of non-operational obligations like taxes or interest payments or capex to maintain your stores. I like to focus on cash flows when I do this sort of analysis, because so much of modern accounting is designed to obfuscate or shade this most basic investment question: where does the cash come from and where does it go?
Those are the numbers. Now here's the story for Bust Out 1.
Bust Out 1 was orchestrated by CEO Steve Temares and company founders Leonard Feinstein and Warren Eisenberg after the disastrous 2013 Christmas shopping season. Total fiscal year operational metrics were fine! In fact, FY 2014 is the absolute peak for BBBY in cash from operations and free cash flow. But Christmas 2013 revealed the internal rot (tired stores, blah inventory, heavy discounting) and external competition (Amazon in particular, but others, too) for all to see, and the stock price took a big hit, going from $80 per share at the end of 2013 to just under $60 by the middle of 2014.
In response, Temares and the board announced a Strategic Plan! TM to reinvigorate the company, complete with a $1.5 billion bond offering, the first debt in company history. What was at the core of this grand plan, you ask? Well of course there were words like "building a leading e-commerce presence" and "targeted acquisitions" and "commitment to excellence", but the main plank of the 2014 strategic plan and the only thing management actually executed on was simply this: Stock Buybacks! TM.
In 2014, as cash operating margins declined 200 bps and cash from operations declined 15% and free cash flow declined 20% from the year before, Bed Bath & Beyond borrowed $1.5 billion and bought back $2.2 billion in stock.
Over the next five years, until CEO Temares was fired and founders Feinstein and Weisenberg were kicked off the board in May 2019, Bed Bath & Beyond bought back an additional $2.2 billion in stock even as cash operating margins went from 12% to 5% (I mean ... good lord) and free cash flow declined by 70% from the FY 2014 high water mark.
Over the 6-year period of Bust Out 1, the board and management of Bed Bath & Beyond spent $4.4 billion buying back their own stock on total free cash flow of $3.6 billion. As their stores deteriorated and their margins collapsed, this company spent ALL of their free cash flow and then $800 million MORE buying back stock.
Now that's a bust-out!
How did this personally benefit Temares, Feinstein and Weisenberg? Well, I compiled the 100+ SEC filings from these gentlemen to find out.
Steve Temares is a real estate lawyer who was hired by the company as their general counsel in 1992 and worked his way up the ranks. He's not a founder. He's not an entrepreneur. He's a real estate lawyer who went from general counsel to executive VP to COO to CEO in 2004. I do not think it was an accident that Bed Bath & Beyond also instituted their stock buyback plan when Temares was named CEO.
As CEO, Temares was granted a total of 5.2 million shares of stock over his tenure, either as options that he immediately sold on exercise or as stock grants at no cost. He never bought a single share of Bed Bath & Beyond on the open market, but was reloaded by the board of directors every few years.
As CEO, Temares sold 4.3 million shares of stock for $148.4 million. This is net of all option exercise costs. This is in addition to his cash salary, bonuses and benefits, which averaged more than $4 million per year during the Bust Out 1 period. This is solely in connection with his personal holdings and is separate from the dozens of transactions associated with the family trust he established to exercise and sell additional BBBY options. After being fired as CEO, Temares sold an additional 900,000 shares for an estimated $18 million. This is in addition to his cash severance package of $36 million. In sum, Steve Temares received well in excess of $200 million in cash from Bed Bath & Beyond shareholders, the majority of this during or after Bust Out 1.
As for co-founders Leonard Feinstein and Warren Eisenberg, after the stock buyback program was introduced they each sold more than 10 million shares for an estimated $300 million. Each. This is in addition to the CEO-level salaries, bonuses and benefits they received as Co-Chairmen of the Board (my fave benefit was $230,000 in car service allowances per year; I mean, how is that possible?). This is in addition to the millions spent to make all-cash acquisitions of retail operations started by their sons, most famously $86 million in cash to acquire buybuy Baby from Leonard Feinstein's son, including the retirement of $19 million in debt owed to the Feinstein family.
Honestly I don't get as worked up over founders taking huge amounts of money out of a company as I do over managers, and if Bed Bath & Beyond had remained a private company that the founders decided to suck dry and leave to their kids ... more power to 'em. But that wasn't what Feinstein and Eisenberg did. They took the company public, dominated the board with Steve Temares, and used stock buybacks to prop up the stock price and sell tens of millions of shares into the open market. Feinstein and Eisenberg were old school merchants! You'll never convince me that they didn't understand exactly what was happening with the accelerated operational decline of the company from 2014 forward and exactly what were the consequences of spending 122% of free cash flow on stock buybacks.
It's no wonder that Temares, Feinstein and Eisenberg were all kicked out of the company in 2019, but by then the fatal damage was already done.
Bust Out 2 (2021 – 2022)
It's hard to describe how rare it is for activist investors to win a proxy fight against an entrenched CEO and Co-Chairmen of the Board who founded the company! But that's exactly what three activist investment firms — Legion Partners, Macellum Capital and Ancora — did in 2019 when they acquired 5% of the company stock and successfully marshaled support from the other big institutional holders. The 168-page deck where they make their case is a thing of beauty, and I've made it available for download here. Seriously, if you are at all interested in this stuff, it's excellent work.
With much fanfare the activists brought in a new strategy and a new CEO (Mark Tritton) from Target that November, right before the all-important Christmas season which ... oops ... did not go particularly well. I'll repeat the financials chart with the post-proxy fight years highlighted to illustrate the point.
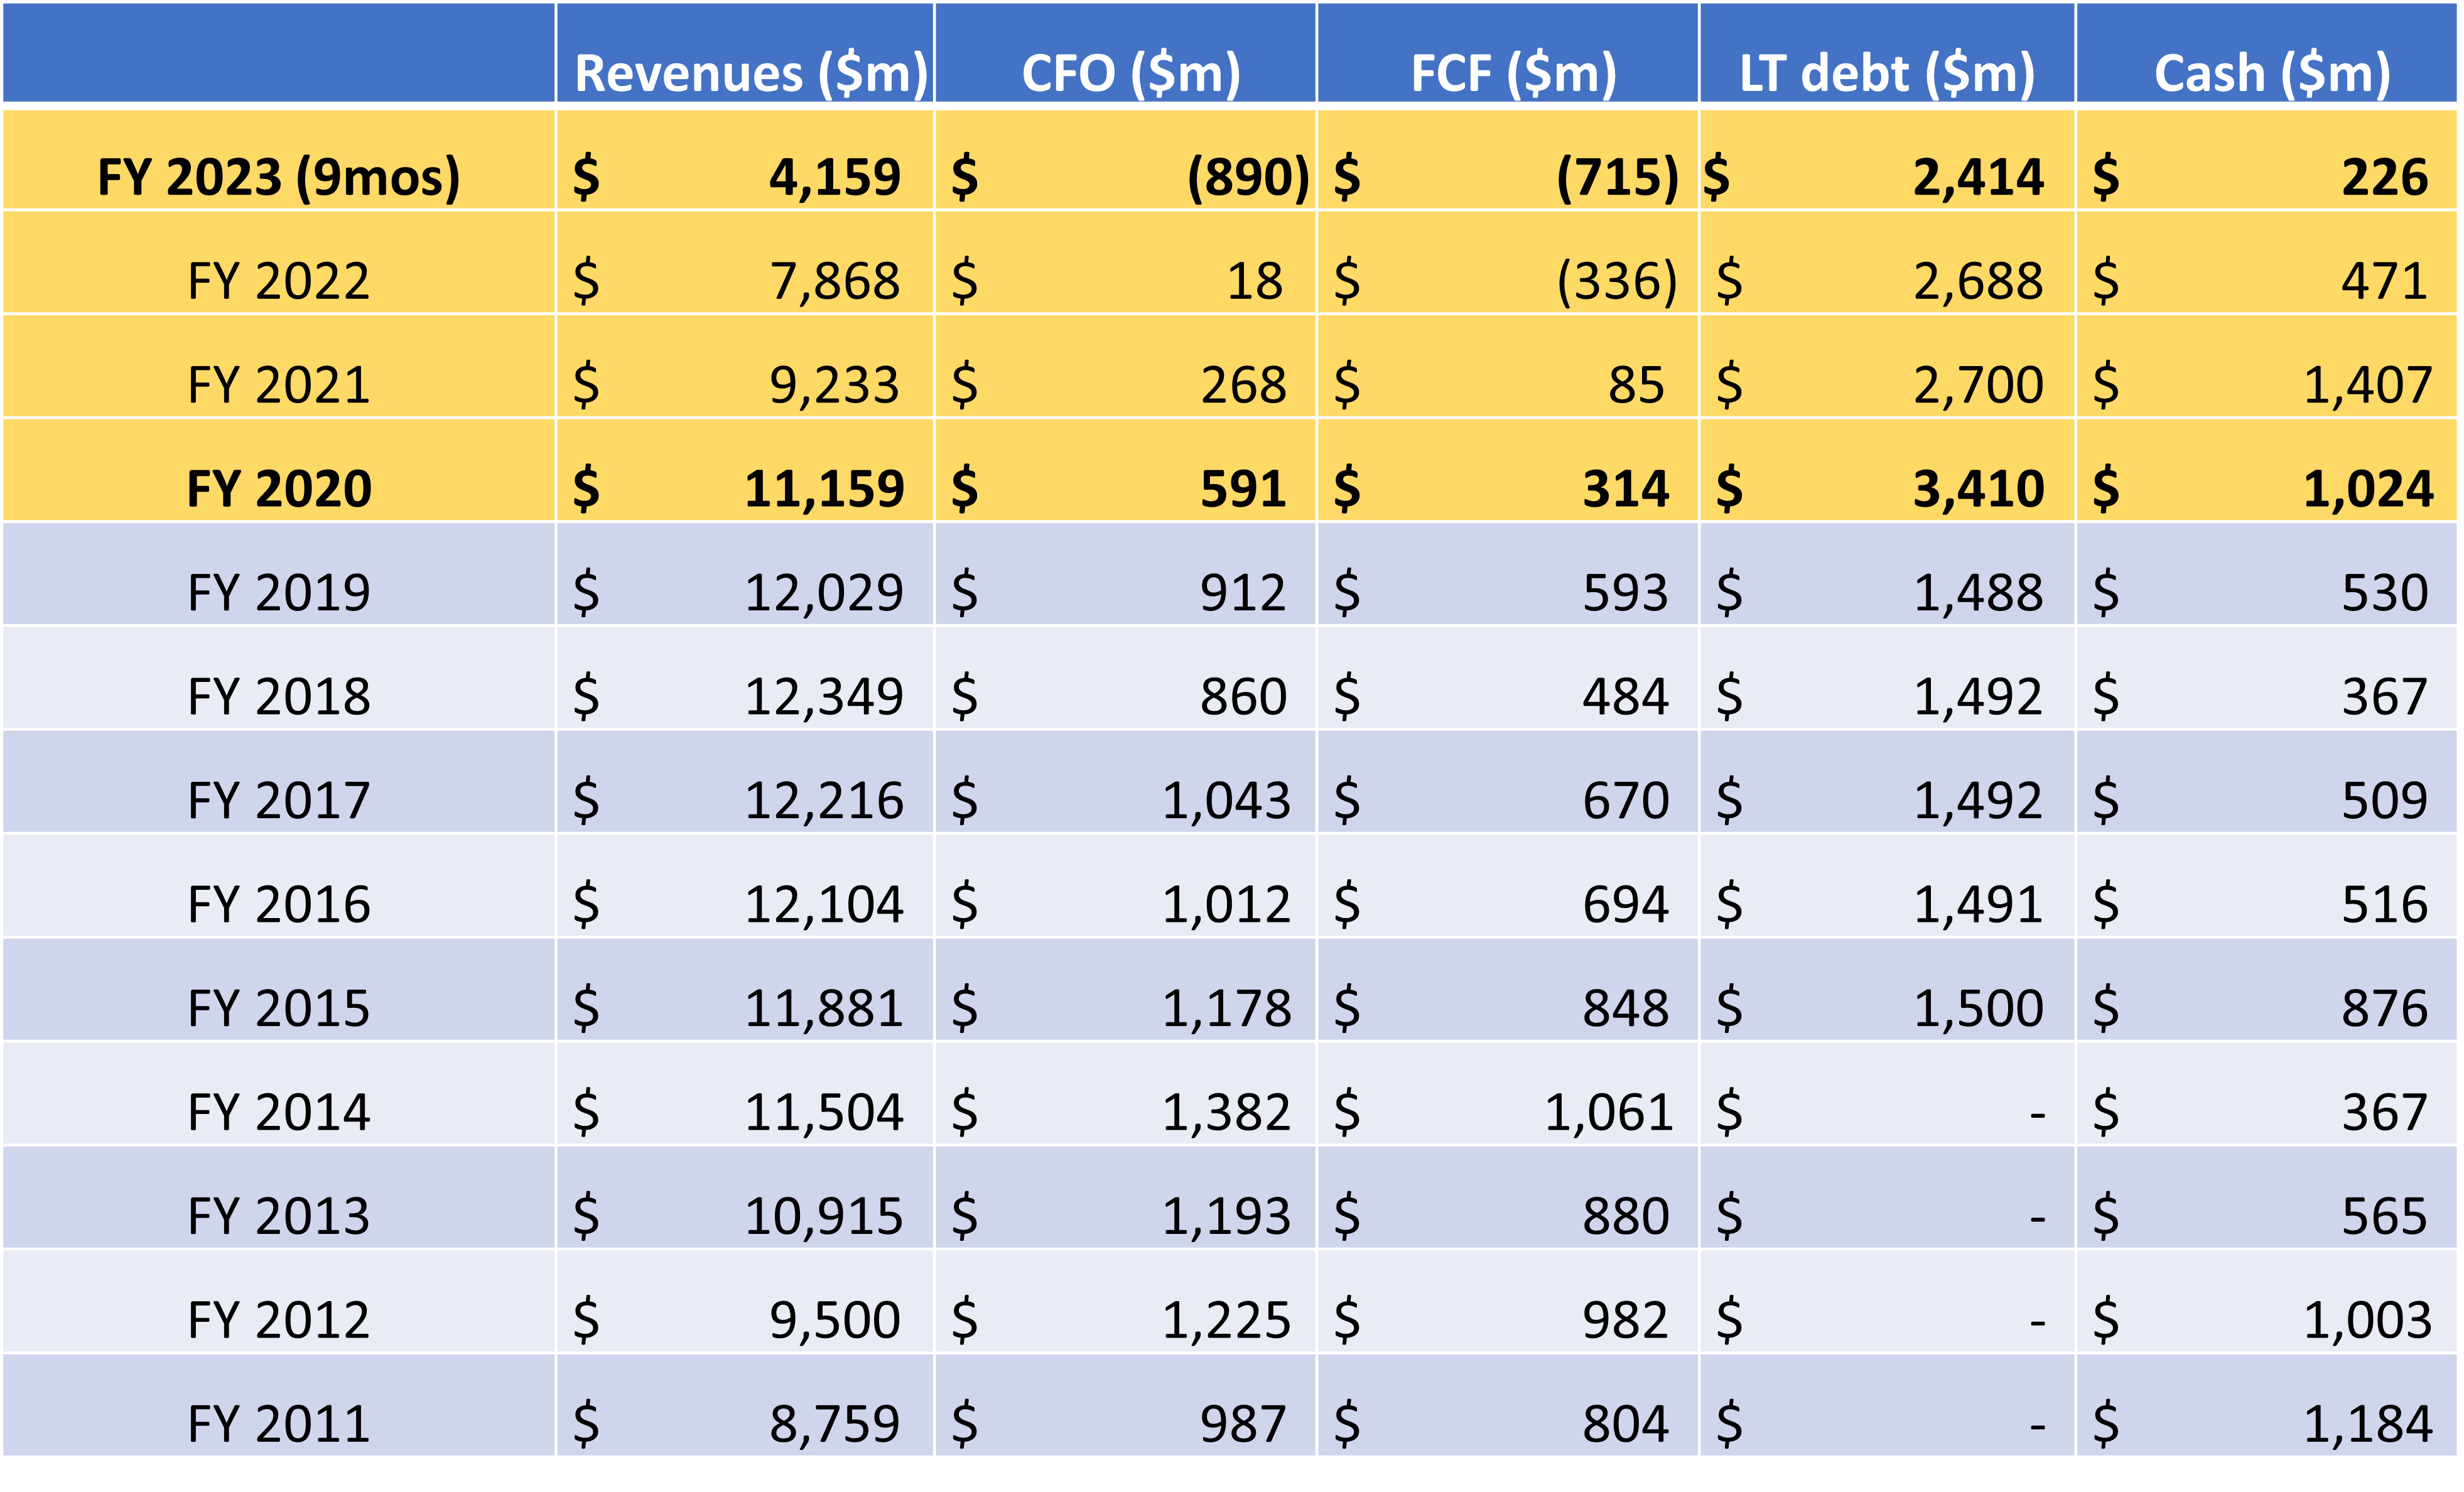
Bed Bath & Beyond financials (source: 10Ks, 10Qs, Bloomberg)
Again, recall that when we're talking about the 2019 Christmas season, that's entirely within the FY 2020 results. Not only did the company take on $2 billion in new long-term debt as part of the management and board overhaul, but cash from operations and free cash flow continued their steady decline and the fiscal year ended poorly. And then came Covid.
Look, I have no idea if Mark Tritton and the new team would have been able to turn around Bed Bath & Beyond under the best of circumstances. Honestly, I doubt it. But once Covid hit in March 2020 (so the start of FY 2021)? Not a chance. And you can see how the operational metrics plunge.
By September 30, 2020, all three of the activist funds that led the proxy fight to replace CEO Steve Temares and the entrenched board just 15 months earlier had sold their entire stakes. They're out! In 15 months! Macellum never had much stock in the deal to begin with, so I don't know how they fared. Ancora had a peak stake of 1.6 million shares, and it looks like they made a little profit. Legion Partners had by far the biggest stake, with peak holdings of 5.7 million shares, and it looks to me like they probably cleared a profit of $5-10 per share? Clearly these insiders used their insider status to see that there was no turnaround possible and exited before that became obvious to the world. But I don't consider this a bust-out because I don't see a concerted effort to prop up the stock or use a bullshit narrative like Stock Buybacks!TM to cover their exit. Was it an insider, privileged information sale that should have given any investor a clear signal to run away? Sure! But a bust-out? No, I don't think so.
In fact, the stock went to new post-proxy fight highs in early 2021 on the heels of a better than expected Christmas season and a general lift from a Covid re-opening trade. On that basis, the activist investors got out too early. But on an operational basis ... everything continued to get worse for the company and a new bust-out formula was hatched. How do I know? Because the company starts buying back stock again to prop up the stock price.
In FY 2022, with collapsing same store sales and a $336 million free cash flow deficit, Bed Bath & Beyond bought back $590 million in stock and depleted its cash and cash equivalents from $1.4 billion at the start of the fiscal year to less than $500 million at the end.
CEO Mark Tritton sold $5 million worth of stock grants into this renewed stock buyback program.
COO John Hartmann sold $3.5 million worth of stock grants into this renewed stock buyback program.
This is now the end game.
Enter Ryan Cohen, the 36 year-old activist investor who spearheaded the meme stock revival of Gamestop and has been its Chairman since 2021. No one can sniff out a bust-out like Ryan Cohen.
At the tail end of FY 2022 (so February 2022), Cohen started buying stock and call options in Bed Bath & Beyond, creating a >5% position by February 24 (7.8 million shares and 16,700 options contracts acquired for a total cost of $121 million). He notified the board on March 6, 2022 and the letter was released publicly on March 7. The stock spiked from $15 or so (Cohen's average purchase price for his shares) to $22 and change, about a 50% jump. On March 24, Cohen signed a cooperation agreement with the board, where he agreed not to take his stake above 19.9% (as if he had any intention of doing this anyway), and in exchange the 11-person board was to be expanded to 14, with Cohen appointing the 3 new board members.
At which point all the meme investors who were expecting some masterstroke by Cohen ... selling buybuy Baby for $5 billion? taking the company private at $40? squeezing those darn short sellers and crushing the demon-in-human-form we know as Ken Griffin? ... were left a tad disappointed. Is that all there is? At which point the BBBY stock price resumed its inexorable path down, down, down.
By May, Cohen's position was underwater. And then CEO Mark Tritton was fired. By July, Cohen's position was WAY underwater. This shall not stand!
Going into August, 2022, 103% of the Bed Bath & Beyond float (shares available for public trading) had been sold short. Now, this is not crazy. It is not prima facie evidence, as the Reddit meme stock apes would tell you, of naked shorts (stock shorted without a borrowed share to support it) or of the demon-in-human-form we know as Ken Griffin perverting markets from Citadel's offices in Mordor Chicago. Why not? Because of the enormous daily trading volume in Bed Bath & Beyond! When far more than 100% of the float changes hands every day, it's really not so hard for the shorted float percentage to also be more than 100%. But still ... this is a very high short interest for any stock, no matter the daily volume, and the drums of Short Squeeze! TM started pounding VERY, VERY LOUDLY throughout meme stock world.
To be clear, I have zero evidence or knowledge that Ryan Cohen encouraged this Short Squeeze!TM drum-pounding. I know that he had 121 million reasons to encourage it. I know that his 121 million reasons had a loss of about $80 million coming into August. I know that there is no human on the planet with more skill or experience in encouraging a Short Squeeze!TM drum-pounding than Ryan Cohen.
For whatever reasons, there was a massive short squeeze in BBBY in the first two weeks of August. Massive! In late July, this stock was trading at less than $5. On August 16, the stock hit an intra-day high of more than $29! That's like a 600% advance in three weeks. Insane.
And at that moment, at a top-tick price of $29.22, Ryan Cohen began to sell. He sold it all. He sold 7.8 million shares of stock on August 16, plus 16,700 call option contracts with strike prices in the 50s and 60s, for total proceeds of $189 million.
In three weeks, by virtue of a meme stock short squeeze that appeared out of nowhere on the Reddit meme stock boards, Ryan Cohen went from an $80 million loss on his Bed Bath & Beyond position to a $68 million profit. Within a month, the stock was back under $10. Within two months, the stock was back under $5.
Now that's a bust-out!
LULZ (February – March 2023)
The lulz period in 2023 is a variation on the meme stock Bust Out 2 of Ryan Cohen. In a nutshell, new company management worked with an external "investor" (you'll get the reason for the quotation marks in a minute) to sell hundreds of millions of new shares of stock a few months after the Ryan Cohen debacle. I feel gross just talking about it, so if you want more detail, please check out the yeoman's work that Bloomberg's Matt Levine has done on this.
Coming into 2023, Bed Bath & Beyond was functionally bankrupt, with negative cash flow from operations, negative growth prospects, and long-term debt of approximately $2.5 billion. No one, least of all BBBY management (Sue Gove, interim CEO since June 2022, signed on as ‘permanent' – lol – CEO in October 2022), had any illusions about what the future held for the company. This was now a work-out. The equity was worthless, and the only question was how the corpse of the company would get chopped up among the bondholders for some partial recovery. That's typically something that gets worked out in bankruptcy court, and it's a brutal, depressing, knife-fighting process. But then someone had an idea.
"Hey, these meme investors are degenerate gamblers. They're easily confused and manipulated, and frankly they're not terribly smart. It seems like we as BBBY management would be abdicating our fiduciary responsibility — not to mention our chances of getting a good job after this company winds down — if we did not take every opportunity to sell them worthless stock in our functionally bankrupt company for cash that we could could hand over to the bondholders. I think the bondholders would really appreciate that and did I already mention the part about getting a good job after we're done here? Oh, I did? Well, bears repeating, right?"
Now I suspect that this idea did not actually originate with Sue Gove and her team, or at least the practical implementation of this ("umm, how can we sell stock in a company that we know is functionally bankrupt without ... you know ... going to jail and all that?") did not originate with Sue Gove and her team. I suspect this idea came from a bondholder-associated hedge fund, law firm or investment bank — organizations filled with very smart individuals who do nothing else all day but dream up rapacious yet (arguably) legal ideas that will separate grown men, weak men, from their money. Ideas like this:
"Hey, meme investors, we are a probably-bankrupt company that wants to sell $1 billion worth of stock. You should definitely do your own due diligence on Reddit for what happens if we declare bankruptcy, but there's a chance that $1 billion is enough for us to have a Turnaround!TM. Also, take a look at what happened to the stock of Hertz after it actually declared bankruptcy. To the moon!"
Now we know what you're thinking. You're thinking that you already got burned with that whole Ryan Cohen thing, and we totally don't blame you. But now the stock is so much cheaper! You can buy so many more shares now than you ever could six months ago. Plus, this time you'll be buying your stock with The Smart Money!TM. Yes, we are announcing a deal where this hedge fund institutional investor called Hudson Bay Capital Management has already bought the first $225 million of our stock offering, and they're committed to buying another $800 million. They're gonna buy the whole offering! Honestly, it's lucky for you that we're still a publicly traded stock because otherwise you wouldn't be able to tag along on this sweet, sweet deal. Yes, we are required to provide a public filing of our agreement with Hudson Bay, but the language is really complicated and hard to read, almost intentionally so. Lawyers, amirite? What's that? Did someone say Short Squeeze!TM? LFG!!!!
In truth, Hudson Bay was a cut-out, an intermediary who bought the equivalent of hundreds of millions of shares in new stock from Bed Bath & Beyond only to turn around and sell all of it into the open market to meme investors. Selling these hundreds of millions of new shares would obviously drive down the price of the stock, but Hudson Bay was given enough of a discount and enough warrant coverage and other goodies such that — so long as trading volume remained robust within the meme investor crowd — they were basically guaranteed a healthy profit on their trade here. And if the stock price got really low (70 cents per share or thereabouts), then the deal was off and they had no more obligation to participate.
Over the active course of this cut-out arrangement, from February 6 to March 30, Bed Bath & Beyond received approximately $360 million from Hudson Bay for preferred shares and warrants, which Hudson Bay translated into at least 300 million shares of common stock which it sold into the open market. The average price of BBBY stock over that span (leaving aside the pop on February 6 to $5.80) was approximately $1.50, which would work out to about $90 million in profits and a 25% return for Hudson Bay ... not bad for a two-month bust-out!
After the termination of the Hudson Bay cut-out arrangement on March 30 and prior to its formal bankruptcy filing on April 24, Bed Bath & Beyond continued to sell hundreds of millions of new shares directly into the market through a series of at-the-market offerings. I figure they were able to raise at least another $100 million in cash from these sales, making a grand total of about half a billion dollars over a three month span from this final (?) squeeze of the meme investor orange.
Half a billion dollars.
Nothing illegal about it. All wagers by grown men, free to gamble away their money in whatever way they see fit. Grown women, too, I guess, although not for the first time I am struck by the fact that the weak, degenerate gamblers in these stories are 99.99% male. (Hold that thought, please, for the last section of this note!)
These grown men, these meme investors, aren't particularly upset about losing half a billion dollars. They're not fazed by it. As I write this note, the common stock of a no-longer-functionally-bankrupt-but-now-formally-bankrupt Bed Bath & Beyond trades at $0.17 per share. The average daily volume over the past 65 days is 123 million shares. If Bed Bath & Beyond could issue new equity from within formal bankruptcy I'm sure they would continue to find buyers. They would continue to find grown men to perpetuate the bust-out on and on, even through bankruptcy.
Which gets me to this.
The United States of Bed Bath & Beyond
At a large enough scale, the bust-out goes on forever.
Sure, it becomes more and more of a lulz bust-out over time, relying more and more on cut-outs and cartoons, more and more on ‘arguably' legal ways to separate grown men from their money (and their votes). But it goes on and on all the same.
In the American context, my personal view is that Bill Clinton and George W. Bush presided over Bust Out 1, Barack Obama orchestrated Bust Out 2, and Donald Trump kicked off the lulz period, which we are now squarely in. I mean, how can you understand Trump and Biden as anything other than lulz?
In the American context, my personal view is that all of the signature economic policies of the past 30 years — ALL of them, from NAFTA to the Bush Tax Cuts to TLGP/TARP to QE1/2/3/infinity to Obamacare to the Tax Cuts and Jobs Act to PPP to the American Rescue Plan to the Inflation Reduction Act – have been bust-out policies.
And it's not going to stop.
It's not going to stop because we are increasingly a nation of weak men, degenerate gambling men, men who in their desperation for wealth or recognition will bet more than they can afford to lose over and over and over again. And I'm not talking about a loss of money, although yes that, too. I'm talking about a loss of autonomy of mind, where the weak man willingly gives away his very identity to a political party or economic creed if they will just allow him to be part of the action. Because in the end that's all the weak man, the degenerate gambling man, has left. The action.
It's not going to stop because we are increasingly a nation of rapacious men, clever-edging men, men who discover early on that they're damned good at playing the game of take-the-sap's-money and never realize until it's too late that the table stakes for this particular game are ... well, being damned themselves. And I'm not talking about being damned in the religious sense, although yes that, too. I'm talking about a loss of humanity, where the rapacious man willingly gives away his very identity to a corporation or business partnership if they will just allow him to continue winning the game. Because in the end that's all the rapacious man, the clever-edging man, has left. The winning.
There are lots of Old Stories about times like this, when our nation itself seems like it's sick, when our society and all within it seem to be infected by avarice and wrath and pride and lust and envy and sloth and gluttony just as surely as any virus. My favorite of these Old Stories likens it to a box of evils opened and loosed on the world.
But you know what remains and is preserved when the box is opened, right?
Hope.
I started this note by writing that the story of Bed Bath & Beyond was maybe, just maybe, a story of hope, and that's how I'm going to finish it.
I am hopeful that the reality of the Bed Bath & Beyond bust-out — crappy stores and crappy management and overwhelming debt ending in failure — will encourage weak men and rapacious men alike to see beyond the narratives of market game-playing and control.
I am hopeful that the reality of the American bust-out — crappy institutions and crappy leaders and overwhelming debt ending in failure — will similarly encourage weak men and rapacious men alike to see beyond the narratives of political game-playing and control.
I am hopeful, not in the common but false usage of the word as 'optimistic' or 'thinking it likely', but in the true sense of the word as being 'full of hope'. I am full of hope that weak men will choose to reclaim their autonomy of mind and that rapacious men will choose to reclaim their humanity.
I'm not optimistic. But I am very, very hopeful!
Comments
Ouch painful to read as I’m quite invested in this one.
I hope you are wrong and I’m not that weak or gambling.
Turns out definitions actually matter
Curious what you hope Ben is wrong about here?
Well I think his perspective on Ryan Cohen seems slanted. He hasn’t created the typical stock buy back programs in the companies he runs. I know Ben has a huge problem with that.
He has also been pretty successful in turning around GME regardless of the “meme” investing movement. Back to basics and for the most part not overleveraging or wasting money on stupid projects.
More than that, I think he’s been more organic trying to build a community through the NFT culture and his presence on twitter is aligned with a lot of what Ben says: his brave stance against covid response and partisanship.
So in a lot of ways I think Ben has things in common with Ryan.
As to his characterisation of the people invested in the company, yes there are people who want to make a quick buck or grift for squeeze^TM but there are also genuine people who shop at the stores and see it as something worth protecting over the consolidated experiences of amazon or wallmart. Just from personal experience of interacting with them.
As someone who doesn’t care to have a kid and doesn’t live in US, their love of the store kinda touches me. To read Ben characterise that sentiment with a broad brush of 99% grifty men and gamblers does itch a little.
As to his perspective on Tritton he was fairly soft and I think he didnt touch upon him accelerating the stock buy back program:
https://www.bloomberg.com/news/articles/2021-11-02/bed-bath-beyond-soars-on-share-buybacks-plans-for-marketplace?in_source=embedded-checkout-banner#xj4y7vzkg
I can’t access it due to paywall.
But why is this not considered a bust out? Plus I think he was excessively paid relative to the market cap and comparative roles in retail…
But I hope he’s wrong because I’m hoping for restructuring which doesn’t wipe out the shareholders who bought for various reasons. I think Ben mischaracterises that as gambling when some people believed in the company or other figures. It was actually an act of good faith and pretty good intentions for some people, which being rewarded with being wiped out seems unfair and the problem with society today; everyone’s trying to grift.
So yes, I hope he’s wrong about the management and Ryan Cohen and hopefully the community I joined wasn’t false.
But either way, learning curve. I’m happy to be a brain to be picked in this scenario because I’ve been pretty involved from the beginning til now.
Just a marvelous note. I would love to see a bigger discussion about each of the bust-out phases from Clinton to Biden, and see if we can’t manage to detect (with the gift of hindsight) how obvious they were while they happened.
Thank you Ben for your clean explanation in a world filled with spittle-flecked hysterics. The forces you describe can do anything but stop.
Tritton was absolutely part of Bust Out 2. He was 2A and Cohen was 2B. It’s the proxy activists who brought Tritton in that I don’t consider to be part of a bust-out. They were long gone before the buyback program was reaccelerated by Tritton and the board.
Cohen is a con man. He’s also a good founder who created something useful and was rewarded for it. Those two things can live side by side. He may well do great things with GME. I hope he does. But he knew that his minions on Reddit were exit liquidity and he treated them as such. Is he a villain or a hero? Yes.
Thanks for the clarification.
Also when Ryan sold his stake, I believe he sold to a private entity. I’m not sure it’s simply that he dumped the shares on the open market.
But this whole thing was a lot more convoluted than I expected and requires someone probably financially trained to deal with the complexities. You could think of my process like boiling a frog more than gambling. I’m still trying to understand where it will go and I’m not entirely convinced it’s to 0.
If it does, you can find me making a post of having survived a cult later on.
Well it remains to be seen in my eyes currently…
He’s listed as one of the interested parties in the restructure.
Continue the discussion at the Epsilon Theory Forum...