The Zimbabwe Event
January 27, 2021·Money
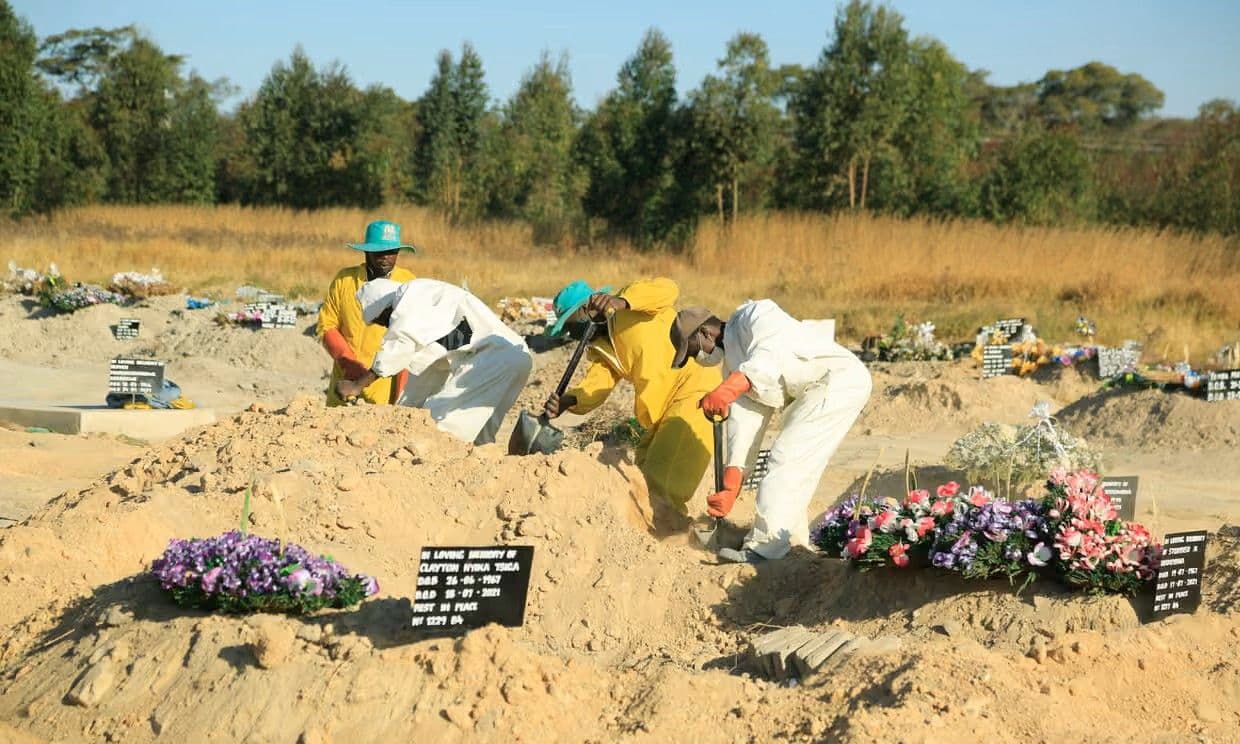
Gravediggers fill in a grave after the burial of another Covid-19 victim at the Zororo cemetery in Chitungwiza, near Harare. Photograph: Aaron Ufumeli/EPA
Over the past week, three senior Cabinet officials in Zimbabwe (including the Foreign Minister and the Infrastructure Minister) have died from Covid. Not gotten sick. Died. More broadly, reported Covid cases and deaths (the unreported numbers are certainly much higher) have exploded in this country of 15 million just in the month of January.
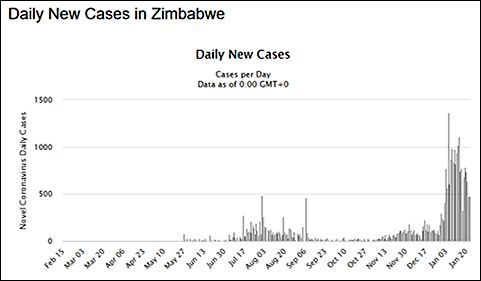
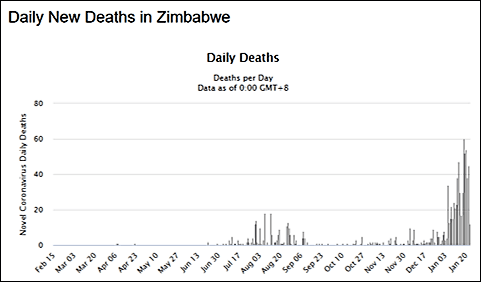
Unlike the ‘Ireland Event’ I’ve been writing about recently, the engine of this human and political tragedy is not the UK-variant virus (B117), but the South African-variant virus (501.V2). This is the ‘Zimbabwe Event’, and I believe it has significant real-world and market-world consequences.
My emails to you about the Ireland Event – an explosion in Covid cases in Ireland over the last few weeks in December, driven by a combination of relaxed social mitigation policies and the introduction of a more infectious SARS-CoV-2 virus from the UK – focused on two questions:
- how likely is a rolling series of B117-driven Ireland Events in the United States? (very, imo)
- where are we in the timeline for the first of these US-based Ireland Events? (2 to 3 weeks from today, imo)
There was a third question embedded in all this, of course, which is what the market response might be to an Ireland Event here in the United States. Again imo, I don’t see this as a similar risk as last March. I really don’t see this as an epic major market smackdown, provided that the Fed and the White House say all the right things about unlimited liquidity support for S&P 500 companies … which they will. But I DO see this as a sharp punch in the nose to all of the dominant investment themes and narratives today: “dollar debasement”, “reflation”, “number go up” (Bitcoin), “commodity supercycle”, “cyclical recovery”, “earnings recovery”, “pent-up consumer spending”, etc. etc.
Is it just one good punch to all risk assets before we return to our regularly scheduled market entertainment of looking through previously unthinkable numbers of deaths and cases to some happy day of fully vaccinated business as usual?
Probably. But more and more I’m thinking it’s a very solid punch. More and more I’m thinking that this is a tradable punch. I say this for four reasons:
- There is a sharp difference in general media coverage of the risk of viral variant spread versus financial media coverage of the risk of viral variant spread. While there’s an almost willful ignoring of the virus variants in major financial media, this is not the case with major non-financial media, where coverage of the news and risks of viral variant spread shows both “coherence” and “strength”, to use our narrative structure terms. I consider this is to be a classic example of financial market narrative complacency, where all of the narrative risks are to the downside for markets.
- There are now four independent medical studies showing that the B117 variant is both more infectious AND more lethal than the baseline virus, versus zero medical studies showing only the same lethality (the original PHE study showing similar lethality has been revised upwards). While the mathematical truth is that increased lethality is not nearly as “dangerous” from a public health perspective as increased infectiousness, from a popular perspective just the reverse is true. Stories of increased lethality carry a lot more narrative punch than stories of increased infectiousness.
- We now have multiple examples of a B117-driven Ireland Event, not just in Ireland and the UK, but also now in Portugal, Spain and Israel, and coming soon to the rest of continental Europe. The ‘Israel Event’ is particularly chastening, as the explosion in Covid cases occurred despite the most advanced vaccination program in the world, with close to 40% of the population now vaccinated. As I mentioned in last week’s note, one of the major consequences of a more infectious viral strain is that the percentage of the population that must be vaccinated before herd immunity brings down the R-number is significantly higher than with a less infectious viral strain, so that even 40% is only a modest help in limiting new infections. Also, and this is highly problematic new news, Israel reports that a single dose of the vaccines that originally contemplated a two-dose regimen is notably less effective than was suggested in clinical trials. Whether this reduced efficacy for one dose of a two-dose vaccine is because of something particular to the B117 variant is unknown.
- The potential for reduced vaccine efficacy AND increased infectiousness AND increased lethality is at the heart of why I think the Zimbabwe Event is so important, both in real-world and in market-world. We don’t yet have any hard evidence on diminished vaccine efficacy for 501.V2, but what we do know is that antibody protection from prior baseline Covid infections, which has shown itself to be very effective in preventing a subsequent baseline Covid infection, is much less effective in preventing subsequent 501.V2 Covid infections. This suggests, of course, that our current vaccines, which largely duplicate the antibody protection that you would get from a prior baseline Covid infection, will be similarly less effective against 501.V2. As for increased infectiousness and increased lethality, we also don’t have as much hard evidence as we do with B117. But the observations in case numbers and deaths we have throughout Southern Africa for 501.V2, from South Africa proper all the way up to Rwanda, are at least as staggering as we see in the UK, the EU and Israel for B117.
In real-world, I think it is impossible to overstate the destabilizing impact of 501.V2 on the politics of a weak state. That’s true in a relatively wealthy weak state like South Africa, much less an insanely poor weak state like Zimbabwe. I mean, the power vacuum that currently exists in Zimbabwe, where three prominent Ministers die within a week and every function of civil government has effectively collapsed … is staggering. Civilian life in these circumstances quickly becomes, as Hobbes would say, nasty, brutish and short. The outcome of these circumstances is ALWAYS war. First a war of all against all, then a war of organized factions, then a war of nations. Some of these wars will be entirely internal to existing borders. More of these wars will cross those borders. Some of these wars will include major powers. War and regime change. That’s the real-world legacy of the spread of these SARS-CoV-2 variants like B117 and 501.V2, and not just in countries like Zimbabwe. South Africa, too. Iran, too. Russia, too.
In market-world, I think it is impossible to overstate the destabilizing impact of a Covid variant that is vaccine-resistant. To be clear, I don’t know that we have that in 501.V2. If I did, then I’d be predicting a lot more than just a transitory punch to the market’s nose. But what we DO have is the start of a vaccine-resistant Covid variant narrative. I hope that’s all it ever is … the start of a vaccine-resistance story that never develops into a vaccine-resistance reality. But for market-world, the mere existence of a narrative like this, even in an embryonic state, is enough to drive tradeable market events. Put that together with recent developments with B117 … put the Ireland Event together with the Zimbabwe Event … and yeah, I think you’ve got a tradeable punch coming to markets.