Personal Investing Pulse
The Pulse
October 19, 2026·Personal Investing Pulse
Executive Summary
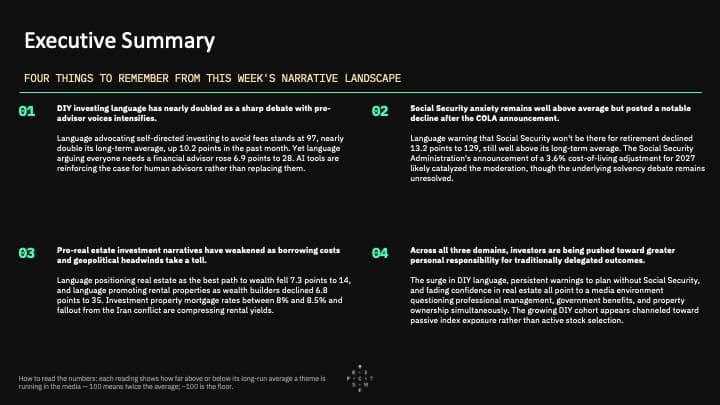
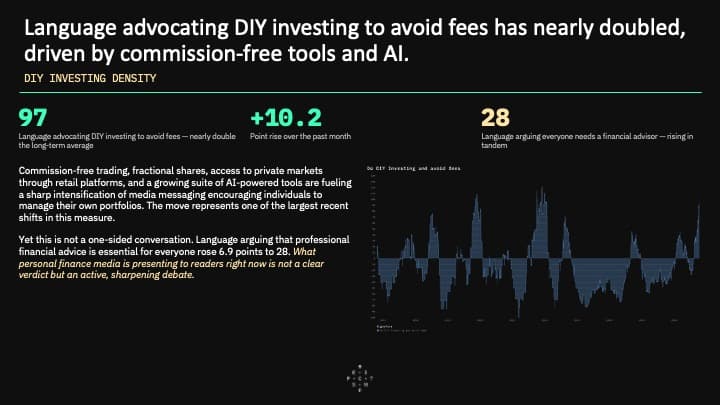
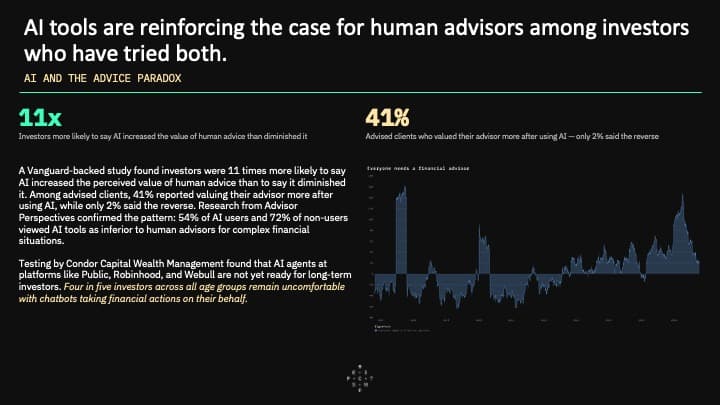
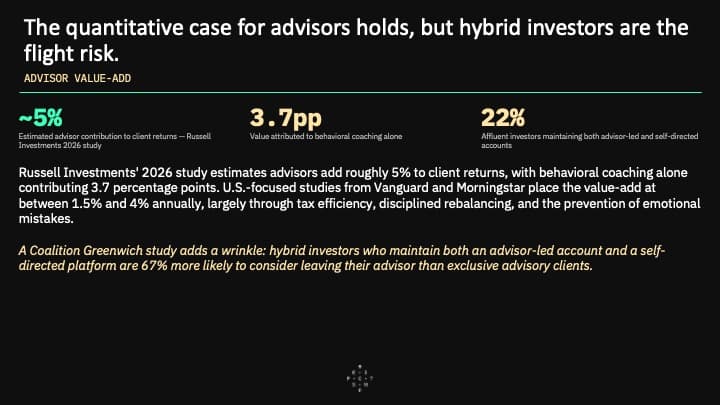
- Financial media is presenting an increasingly polarized debate between self-directed investing and professional financial advice. Language advocating that investors manage their own portfolios to avoid fees has nearly doubled relative to its long-term average, driven by commission-free trading, fractional shares, and AI-powered tools. Yet advocacy for professional guidance is rising in tandem, and early evidence suggests that AI tools are reinforcing rather than replacing the perceived value of human advisors—investors who have tried AI chatbots overwhelmingly report that the experience made them value human counsel more, not less.
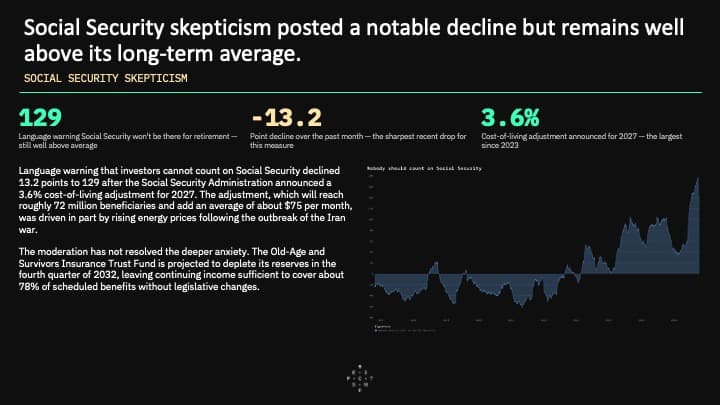
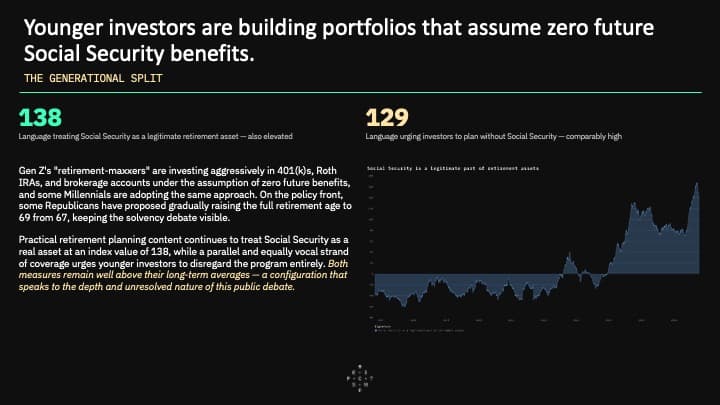
- Anxiety about Social Security's long-term viability remains well above historical norms, but the intensity of that language registered its sharpest monthly decline in our dataset following the announcement of a 3.6% cost-of-living adjustment for 2027. The moderation has not resolved the underlying tension: practical retirement planning content continues to treat Social Security as a real asset, while a parallel and equally vocal strand of coverage urges younger investors to build portfolios that assume zero future benefits. Both perspectives remain elevated simultaneously, reflecting an unresolved generational divide in how the program is discussed.
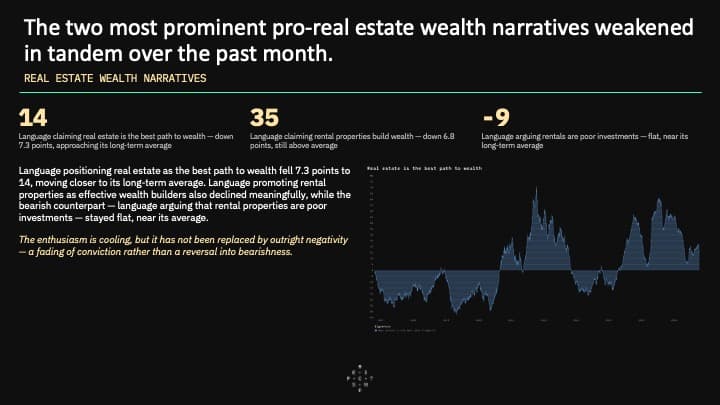
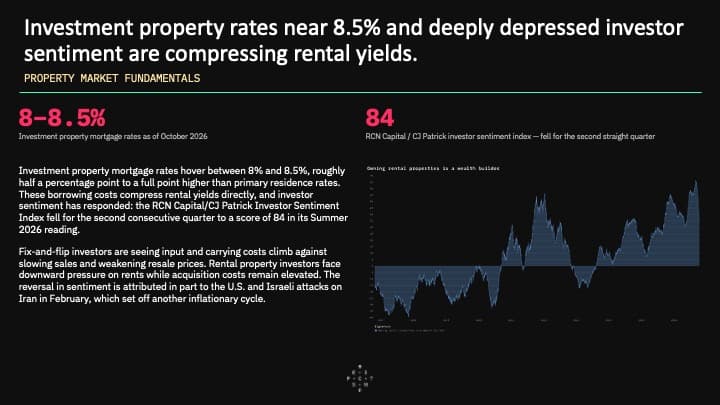
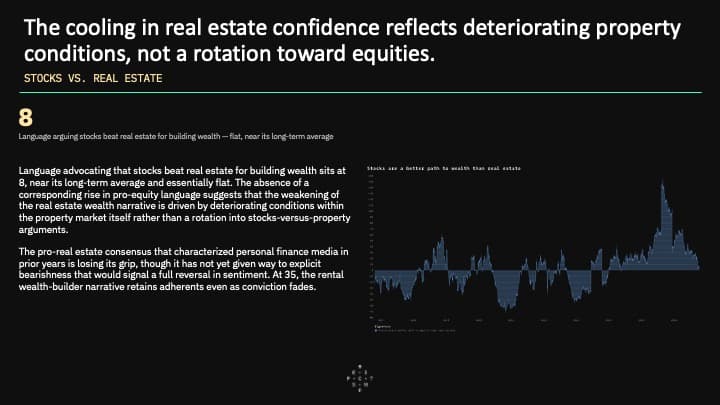
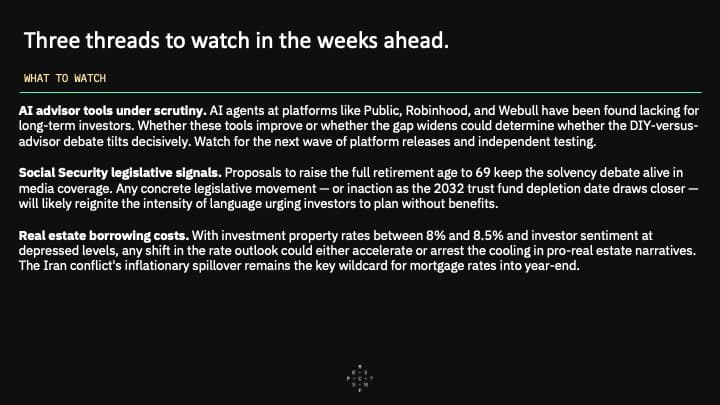
- Pro-real estate investment language has weakened meaningfully, with the two most prominent wealth-building narratives around property declining in tandem over the past month. Investment property mortgage rates between 8% and 8.5%, record-low investor sentiment readings, and inflationary pressures tied to geopolitical conflict have compressed rental yields and dampened enthusiasm. The cooling has not been accompanied by a corresponding rise in language arguing that stocks are superior to real estate, suggesting that deteriorating conditions within the property market itself—rather than a rotation toward equities—are driving the shift.
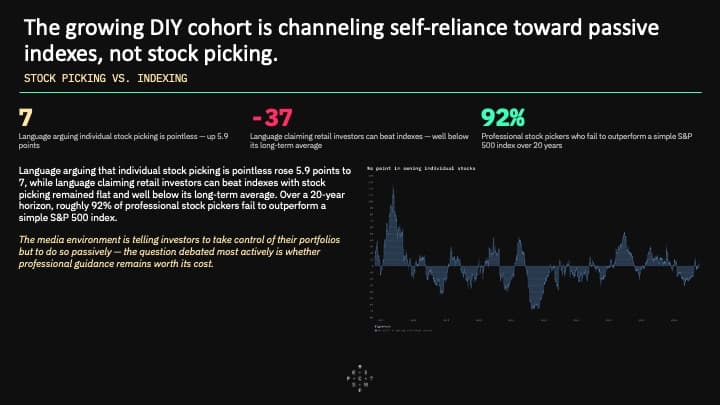
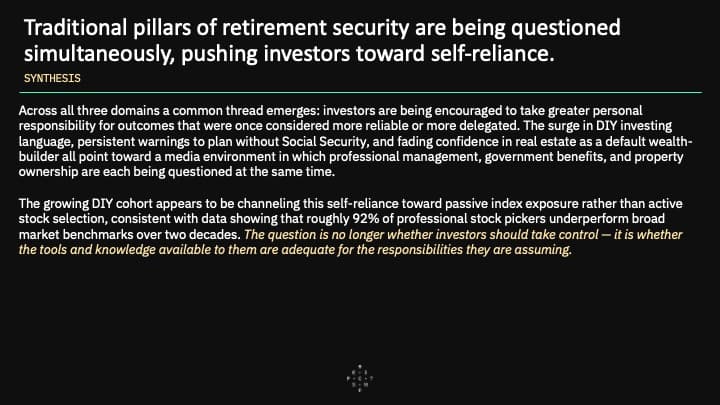
- Across all three domains, a common thread emerges: investors are being encouraged to take greater personal responsibility for outcomes that were once considered more reliable or more delegated. The surge in DIY investing language, the persistent warnings to plan without Social Security, and the fading confidence in real estate as a default wealth-builder all point toward a media environment in which traditional pillars of retirement security—professional management, government benefits, and property ownership—are each being questioned simultaneously. The growing DIY cohort appears to be channeling this self-reliance toward passive index exposure rather than active stock selection, consistent with data showing that the vast majority of professional stock pickers underperform broad market benchmarks.