NGMI
April 11, 2022·Money
Vladimir Putin isn't the only guy who loves a giant shiny table
For the over-40 or crypto-uninitiated or non-bodybuilding-4chan-reading crowd, NGMI stands for 'not gonna make it'.
It's typically used in a tsk-tsk fashion to describe someone who is not going to succeed because they chickened out or fundamentally misunderstood the big picture, as in "Joey sold all his Bitcoin at $40k. NGMI." or "I sent Jimmy the links to my due diligence on Gamestop and MOASS, but he still didn't buy. NGMI." It's meant as an accusation of a lack of knowledge, but in truth it's almost always an accusation of a lack of faith.
Jay Powell and the Fed, hiking rates to Whip Inflation Now? NGMI.
I mean that as both an accusation of lack of knowledge and lack of faith.
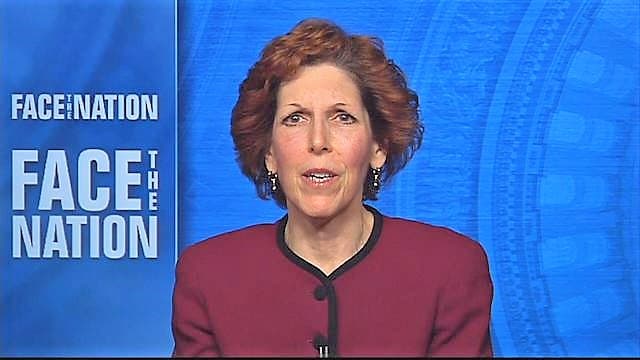
This is Loretta Mester, from a screen shot of her appearance this Sunday on Face the Nation. Mester is the head of the Cleveland Fed and a 2022 voting member of the FOMC, the Fed committee that decides on interest rate hikes. Loretta Mester is a 63-year-old academic economist. She joined the Philly Fed in 1985, a freshly minted Princeton Ph.D., and has never worked outside of the Federal Reserve system. Never.
It's going to seem like I'm picking on Mester, but everything I say about her and every quote I have from her could just as easily be said about or quoted from any other Fed governor. They are ALL part of the same inbred, arrogant, frequently wrong but never in doubt, Soviet nomenklatura-esque priesthood of central economic planning and control.
- John Williams, head of the NY Fed, has never held a job outside of the Federal Reserve system.
- Jim Bullard, head of the St. Louis Fed, has never held a job outside of the Federal Reserve system.
- Esther George, head of the Kansas City Fed, has never held a job outside of the Federal Reserve system.
- Mary Daly, head of the San Francisco Fed, has never held a job outside of the Federal Reserve system.
- Charles Evans, head of the Chicago Fed, has never held a job outside of the Federal Reserve system and academia.
- Raphael Bostic, head of the Atlanta Fed, has never held a job outside of the Federal Reserve system and academia.
- Kenneth Montgomery, interim head of the Boston Fed since Eric Rosengren resigned in disgrace, has never held a job outside of the Federal Reserve system.
- Meredith Black, interim head of the Dallas Fed since Rob Kaplan resigned in disgrace, has never held a job outside of the Federal Reserve system.
- Patrick Harker, head of the Philadelphia Fed, is not a Fed lifer. No, he's an academia and government lifer.
- Thomas Barkin, head of the Richmond Fed, is also not a Fed lifer. No, he's a former senior partner and CFO at McKinsey. LOL. Oh and fun fact ... while she's no longer a regional Fed president (but is on the Fed board of governors), Lael Brainard had a stint at McKinsey as her only job outside of government and academia. So weird.
- And then there's Neel Kashkari, head of the Minneapolis Fed. Neel is just a stalking horse.
Anyhoo ... here's part of the transcript of Mester's interview:
Q: The White House argues the true read of the economy is the strong jobs market. Do you believe employment is so strong, too strong to actually generate a recession?
MESTER: I think we can reduce that excess demand relative to supply without pushing the economy into a recession. So, I'm pretty optimistic we can do this. It'll be challenging, but I think we can do it. And certainly my modal forecast of what's going to happen this year is that the expansion will continue.
"my modal forecast"
Not 'model', but 'modal', as in mean, median and mode, as in run some econometric simulations and see whatever the most frequently observed outcome looks like. It is - and I mean this in all literal seriousness - the modern equivalent of cutting open a dozen rams and examining their entrails to see what the most typical pattern looks like.
Here's what Loretta Mester saw in the entrails modal forecasts last year.
I expect some higher inflation measures in the next couple of months but that is different from underlying inflation levels reaching 2%.
I am unconcerned with inflation running away from us.
I'm not worried about inflation getting out of control.
The Fed needs inflation expectations and real inflation to rise.
I'd like to see inflation rise to 2% or higher.
By the end of the year I expect inflation to be between 3.5% and 4%, with a drop in 2022.
Inflation will be little more than 2% in the next years.
Sept. 24, 2021
But wait, there's more. It's not just that Mester and the entirety of the Federal Reserve economic research team - more than FOUR HUNDRED Ph.D. economists with a budget of literally hundreds of millions of dollars - got the 2021 transition to an embedded inflationary environment completely and utterly wrong, it's also that Mester et al got the prior embedded deflationary environment completely and utterly wrong.
Since early 2009, the Fed has provided the most accommodative monetary policy in the history of man with the express purpose of stimulating inflationary expectations and behaviors to something close to their 2% target. This effort was based on an essentially linear model of the macroeconomic relationship between the price of money and the velocity of money.
Does lowering the price of money from 8% to 7.5% create more risk-taking? Does it increase the velocity of money through the real economy as corporate and household risk-takers are willing to borrow and spend and invest more at 7.5% than they were at 8%? Yes.
How about lowering the price of money from 7.5% to 7%? Yes.
7% to 6.5%? to 6%? to 5.5%? to 4%? Yes, yes, yes, and yes.
It’s a nicely linear relationship (technically the word is 'monotonic', not linear per se, but close enough). Lower interest rates have a specific and direct relationship with risk-taking economic behavior and expectations. The lower the interest rate, the greater the spur to “inflation”, by which central bankers mean risk-taking economic behavior.
But a funny thing happens to risk-taking economic behavior and expectations when the price of money gets close to zero. Not only do you not get the same inflationary bang for your lower interest rate buck, but the relationship starts to go the other way. You start to get LESS risk-taking and inflationary behaviors in the real economy as you get really lower and lower interest rates.
Why?
Because the relationship between the price of money and real world behavior is non-linear.
Just like water.
See, we all know that when gases or liquids get colder, they get denser. They get heavier. The molecules in the gas and the liquid are less energetic as they cool off. They bounce around less. They sink. This is why pool water and lake water and ocean water gets colder the deeper you go. It’s a perfectly linear relationship … the colder the water, the heavier the water … the colder the water, the more it sinks.
But when water gets to 4 degrees centigrade, this nicely linear relationship between temperature and density stops happening. In fact, it REVERSES. It’s not only non-linear, it’s non-monotonic (a ten-dollar word that means reversal). As water gets colder than 4 degrees centigrade, it no longer gets heavier. It no longer gets denser. It no longer sinks.
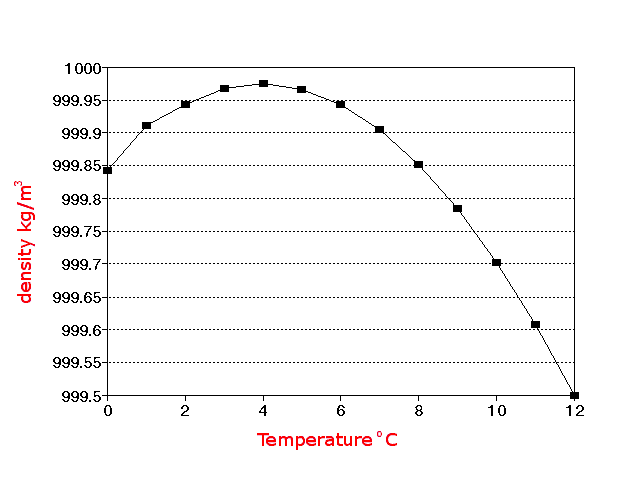
Without this non-linear, non-monotonic property of water, life as we know it would hardly exist.
Every Ice Age would be every bit as much an extinction event as a giant meteor of death. Every lake or pond above or below a certain latitude would be as lifeless as the moon.
It’s a miracle of life that liquid water – the foundation of life on our planet – gets lighter instead of heavier right before it changes state into solid ice.
There’s no reason why this non-linear property of water should exist.
And yet it does.
If you were predicting the behavior of water from a theory of thermodynamics, there is no way you would predict 3-degrees cold water would be lighter than 4-degrees cold water.
And yet it is.
A Song of Ice and Fire (May, 2019):
What's the point here? Just this:
So long as the academic Fed continues to use a set of essentially linear, monotonic models to understand the relationship between the price of money and real world economic behaviors, their predictions will be just as wrong in the hiking stage of ZIRP monetary policy as they were in the cutting stage.
The Fed will overestimate the impact of rate hikes on curtailing inflation in exactly the same way they overestimated the impact of rate cuts on stimulating inflation.
Will hiking rates off the near-zero line make a difference in economic behaviors? Oh yes! Just not the behaviors that the Fed (and the White House) expect.
Cutting rates from 4% to 0% did not spur real world inflationary behaviors, it spurred market world financialization behaviors.
What is financialization?
Financialization is profit margin growth without labor productivity growth.
That sounds like a small thing, but I tell you it is EVERYTHING.
Financialization is the smiley-face perversion of Smith's invisible hand and Schumpeter's creative destruction, where profit margin growth is both pulled forward from future real growth and pulled away from current economic risk-taking.
Financialization is tax and balance sheet arbitrage to leverage laws passed by bought-and-paid-for politicians.
Financialization is stock buybacks to sterilize stock-based comp awarded to entrenched management.
Financialization is the acquisition and burying of smaller competitors to create an insurmountable, anti-competitive moat of scale in every economic sector.
Financialization is the zombiefication of an economy and the oligarchification of a society.
What has the last decade-plus of Fed interest rate cuts and balance sheet expansion given us? Not stable prices with healthy 2% inflation expectations. LOL.
No, the last decade-plus of Fed monetary policy has given us this, the worst stretch of labor productivity growth in the history of the United States of America, not coincidentally occurring alongside the greatest stretch of financial asset appreciation in the history of the United States of America.
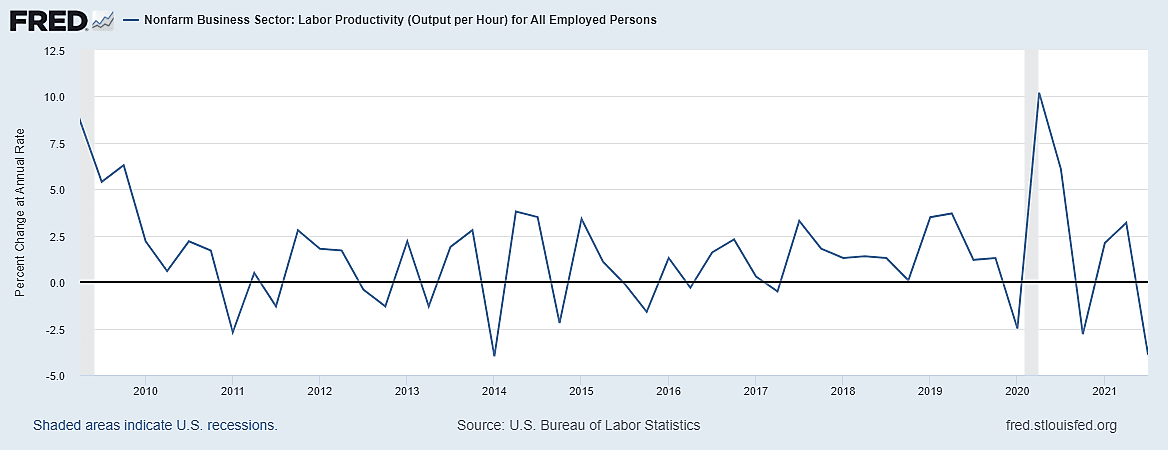
US Labor Productivity, Q2 2009 - Q2 2021
What will Fed rate hikes reverse? Not inflation. Financialization.
What will Fed rate hikes spur? Not number go up. Productivity.
Like this:
Starbucks Corp will pause billions of dollars of stock buybacks to invest more in employees and stores, longtime former chief executive Howard Schultz said on Monday on his return to lead the global coffee chain for a third time.
I think what Howard Schultz did is very smart. I think Howard Schultz gets it. I think that taking the risk of investing more in employees and stores is exactly how Starbucks in particular and this economy in general will grow its way out of embedded inflationary expectations. I think what Howard Schultz announced is great for his company and great for the country!
If you're a Starbucks investor, though, you probably don't agree with me. Here's a price chart for SBUX starting on March 16, when the company announced that Schultz would be returning (again) as CEO. That sharp decline starting on April 4, an 11% free fall in the stock price? Yeah, that was the day that Schultz announced he was going to use their cash to take a shot at boosting productivity instead of the sure thing of stock buybacks.
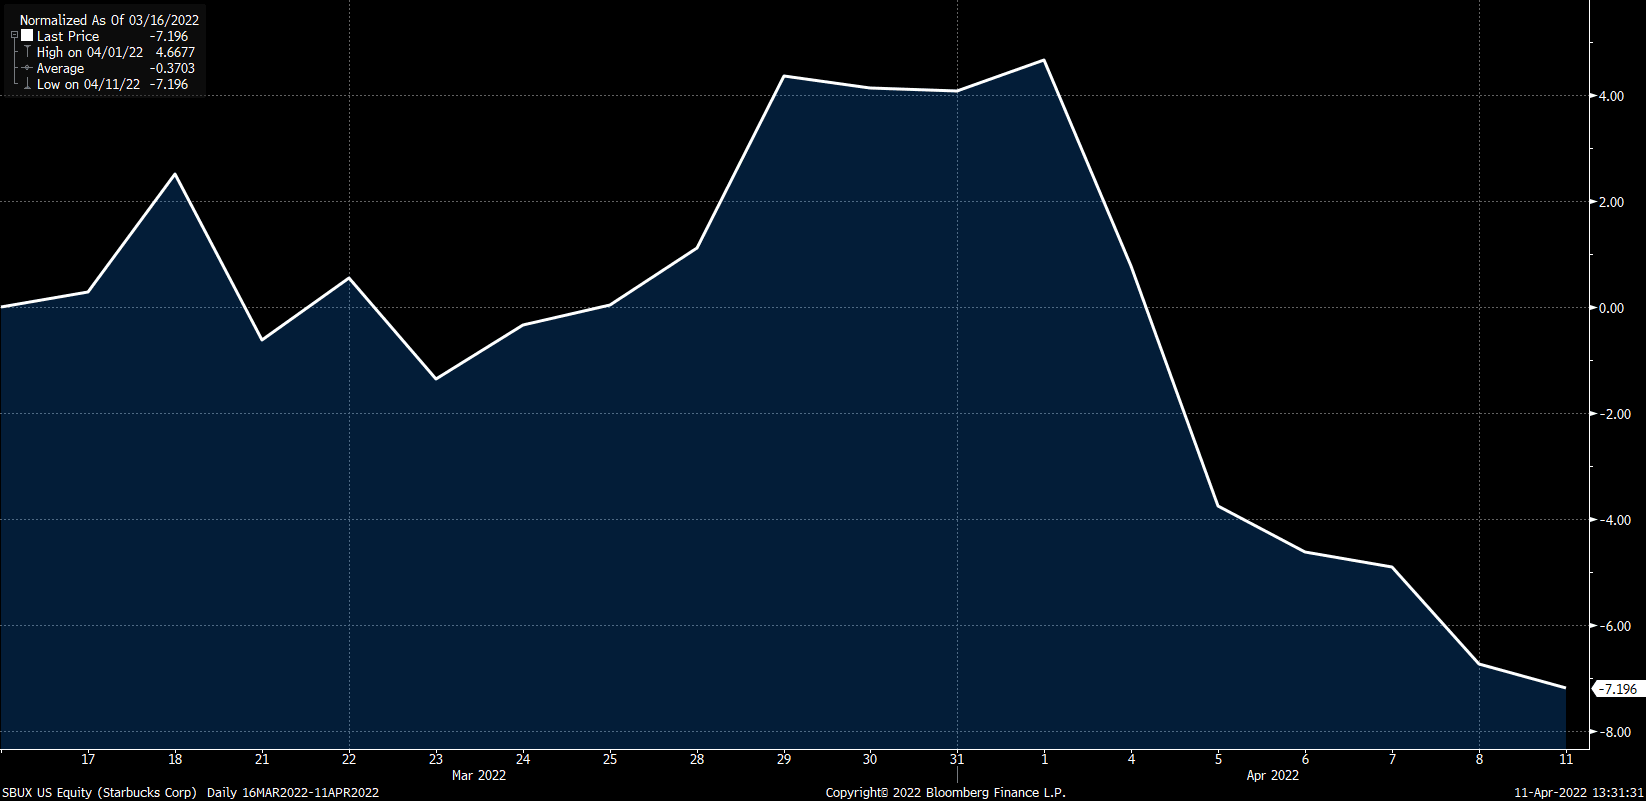
Starbucks (SBUX) % price change, March 16 - April 11, 2022
I figure it will take 2+ years for Schultz's capital allocation shift to translate in a serious way to improved, more robust profit margins through improved, more robust labor productivity. It may not happen at all if all the reinvestment is sucked dry by unionization. It's a risk. A risk worth taking, I suspect, but definitely a risk. Which is why risk takers get paid the big bucks. Or used to, anyway, until the non-risk takers figured out they could get paid even bigger bucks by awarding themselves enormous levels of stock-based comp, converting it into cash comp through sterilizing stock buybacks, and then giving themselves even larger stock awards under the narrative of "aligning interests with shareholders".
So 2+ years for this risk to pay off, if it pays off at all. Meanwhile, Starbucks stock price is down 30% from last summer.
And this is why the Fed NGMI.
Will the Fed rate hikes work to spur real growth and real productivity improvement in the real economy, breaking the vicious cycle of embedded inflationary expectations? Yes! Yes, they will! It's already happening, in fact, with most recent (partial Q4 2021) labor productivity rates jumping to 6.6%, the highest non-recession rate in 15 years!
But the rate hikes won't curb inflation in the way that the Fed thinks they will. Their linear, monotonic models will get this all wrong until rates get back up to some normal-ish risk-free rate ... I dunno, say 3.5% or thereabouts.
And while the reversal of our obscenely financialized world will lead to more and more companies taking real risks in the real economy, just like Starbucks is doing, which is fantastic for the long-term growth prospects of the United States, this process will take years. It took a decade-plus to get into this mess, and it will take a decade-plus to get out of this mess. We don't have that kind of time.
Because capital markets have become political utilities.
Our political system cannot withstand a decade-plus of mediocre to poor returns from capital markets, even though that's exactly what is required to wring out the decade-plus of financialization that Fed ZIRP policies and monetary accommodation have created. Hell, I don't think our political system can withstand more than a quarter or two of this, where every company is a Starbucks down 30%+ and every bond portfolio is having the worst year in 40 years.
The Fed's not gonna make it because:
a) their lack of knowledge, using linear models to predict a non-linear system, and
b) their lack of faith, choosing a path of political expediency over stewardship of American productivity.
What comes after all this? What happens when it becomes common knowledge that the Fed can't "control" inflation the way they predicted?
I think we get a war.
I think we get a man with a plan.
And that's when our troubles truly begin.
Comments
Reading along nodding my head.
Yep. The Fed is clearly incompetent.
Yep. Borrowing money to finance stock buybacks is a misallocation of capital.
Yep. US politics does not allow long-term planning and thinking.
Then “I think we get a war. I think we get a man with a plan”.
Not “We might get a war. We might get a man with a plan”.
For someone as perceptive as Ben to state his predictions that strongly is sadly disturbing. There are many possible future paths but we do seem to be at a point in history taking a dark turn. Stakes are higher than ever before. Will nukes actually prevent conflicts from escalating beyond an ugly simmer or in the end are we just apes with godlike technology who burn our houses down. I’m old enough to have done the “duck and cover” nuclear drills in school. Crouching under my desk now will be just as effective as it was ao many years ago.
I gotta call 'em like I see 'em. No matter where that takes me.
Aside from being inspired to read Kashkari’s Wikipedia bio and getting a little nauseous, the most salient thing I learned from this essay is:
It is useful to think of financialization as path-dependent.
Financialization has been a long time coming, and it’ll be a long time to go. This is because it was not caused by any simple rate equation or other switch flippable by the feds.
Rather, financialization was caused by the separate actions of thousands of managers over the past 20–40 years. It can only be undone by managers, like Schultz, independently weighing the merits of risk-taking and productivity increases and making thousands of separate decisions to take risk in thousands of different ways, which will be industry-dependent.
Whether the rates set by the Fed will be high enough to be “risk-free”, in the eyes of each of these managers, is only one of hundreds of variables that need to align in the right ways in order to reverse financialization.
One place I’m confused after reading this is the precise relationship between our financialization and our inflation. @bhunt writes:
This implies to me that our current inflation is also path-dependent, as “embedded inflationary expectations” are one form of financialization. IOW: all the narratives, the missionaries, the blame, the excuses, the BS for the virus of rising prices, all of these things are one kind of profit margin growth without productivity growth.
So, here’s my point of confusion: I had assumed from other forum threads and reading about the Volcker era that, to a useful approximation, our current inflation is not path-dependent.
IOW, I had assumed that if somehow the political will existed tomorrow to wind down the Fed’s balance sheet and raise the prime rate to (say) 10%, then inflation would end.
If I interpret NGMI correctly, Ben is saying that this is wrong. If these things happened tomorrow, of course we’d find ourselves in a large economic contraction, and but our embedded inflationary expectations would still persist for some time. Depending on how strongly these expectations are now driving our inflation itself, we might also expect inflation itself to persist for quite some time, meaning we’d have The Mother Of All Stagflation.
Am I now thinking about this stuff correctly?
I will be quite poetic to see happening what Ben suggests. The Fed hiking, the economy slowing…and inflation being “stubbornly” high. What to do? More hikes! The economy slows more but inflation continues to be high! A poetic opposite to the 2010s
Not sure if I would put it as my base case, but definitely it’s a neglected risk as it goes against core beliefs economic policy makers and market participants have. Great insight Ben!
As the Fed starts to increase rates, it will be great to use this forum to keep track this if this corporate behaviour (e.g. Starbucks) gains pace. As Ben did on Twitter with inflation last year.
Curious to hear thoughts on who will become the winners and losers in this world (commodity producers vs companies of the gig economy?, bond holders even if they are positioned at the 2-5 year part of the curve?)
Bravo Ben , I agreed with virtually every word , the only issue I might take is that the productivity gains we have seen this year may be ,at least in part , to some people finally getting back into the office. I know our team has been way more productive since getting under one roof.
That is just splitting hairs though .
The FED will chicken out at the first sign of trouble and the next “stimulus” will be bigger than the last two. I wonder if the 8.4% CPI number but lower than expected “core inflation” does not give them some cover to back off a bit.
This post is gold.
Sounds like the same thing I have been expecting to happen for the past decade+…
Agree, but it’s the kind of finality I only thought about and hated to say out loud. It makes sense at D.C. will have to do something to take everyone’s minds off of the huge & increasing loss of their purchasing power, so why not take our Forever Wars! tm from ‘medium warm’ to ‘high’ and see if that works? I hope you are wrong, Ben, because I doubt that empires and oligarchs go gentle into that good night.
I overheard a conversation recently where a man and woman were discussing a sex scandal that had rocked the Christian ministry where the woman worked. When the friend asked if she had hope for the future of said ministry, her reply was “overall I am bullish on the future”. …“bullish on the future.” Someone who clearly works in a completely unrelated field used a market metaphor to express a core emotion, hope.
The “Speculation Layer” is now the Water We Swim In.
When everyday normies are casually using “number go up” symbolism to express hope for a better future, I think the moment number-goes-down for any length of time we’re NGMI. Unfortunately, I strongly suspect Ben is right about this leading to War and a Strongman-with-a-plan.
Thought provoking post, well done.
RE: Howard Schultz Gets It
Maybe. I’m willing to be persuaded by a detailed plan and evidence. But here’s what I argue Howard Schultz doesn’t get:
Succession Planning/Talent Management.
Schultz starts his 3rd bout as CEO, making him the Rocky Balboa of coffee.
With a combined ~23 yrs in the top spot, Schultz has had ample time, power, and resources to invest in talent and processes. Talent management/organizational effectiveness generally includes executive succession planning with identified successors and detailed developmental plans for each key executive.
Whatever Schultz thinks he needs to invest in, it should escape no one that Schultz was at the helm for more years than not over the past two decades.
Giving him the benefit of the doubt, perhaps Schultz’s people investment plan means better coffee, faster, at the same or lower price point thanks to productive, efficient employees. We will see.
I am elated that this note is calling attention to a question of massive importance, that simply no one is talking about and I can’t understand why. That question is:
WHAT is the deal with Putin and his giant tables?
Like.
Seriously. What is up with this? Does he like…have to shout?
I’m a very visual person so this bothers me. I concede that one of the great unspoken casualties of the pandemic is well-staged public figure photography, see, e.g., the awkwardness of this photo that makes me die a little inside from an internal cringe hemorrhage:
But I get it, world leaders are frequently old, so COVID is especially bad for them. The cringe for me in the G7 photo comes not from exactly how it looks, but the fact that I am sure everyone in this photo is fully vaccinated, so the social distance is just pandering to make them appear that they are in solidarity with the common folk. It’s also creepy due to the vague threat delivered with friendly smiles - “public health mandates issued from on high must be obeyed at all times, even when common sense dictates in certain situations that they are totally unnecessary. We are doing it, therefore you are going to do it.”
Well, but okay, it is also just how it looks. None of them but Trudeau know what do with their hands. If it were zoomed in or they could shake hands, or put them together on a glowing orb, or something, then the hand thing wouldn’t be an issue.
Putin is getting old, sure. He wants to social distance, maybe doesn’t trust the Sputnik vaccine. But then why have the meetings in person? I mean, yeah, you want the photo-op. The leader, taking charge, directing advisers, getting after people, for the motherland. But it’s producing a bunch of bad photos. Especially with the imbalanced spatial distribution of advisors/ministers, the interior setting with total absence of natural light (it looks like the Kremlin uses the same lighting guy as your local dentist’s office), this reads more like “paranoid isolated germaphobe” than “maverick defender of the Russian people.”
I’m only 45% joking when I say, to me this is actually the most disturbing signal to come out of the Kremlin. Putin doesn’t look strong, he looks unhinged, but even worse - apparently doesn’t realize that he looks unhinged? I thought this guy was supposed to be a master of manipulation and propaganda - but maybe he’s really more like late-life Howard Hughes with nukes? Maybe it’s not all just yes-men telling him what he wants to hear and it’s really Putin himself who is NGMI?
Now the other brief comment I had about the Fed and interest rates is this:
There seems to be a debate on whether the Fed’s actions will be effective, or whether they have been asleep at the wheel and this thing has gotten out of their control.
For months now I have been asserting to people that it’s neither - the Fed’s actions won’t be effective, but not because they are asleep at the wheel, because THERE IS NO WHEEL. They don’t really know what they’re doing and never did, and in a way it’s not their fault, because carefully controlling the economic behavior of millions if not billions of people, and trillions of dollars in commerce solely by tinkering around with a couple benchmark interest rates - in a way it is absurd to think that this is an effective tool to maintain control?
The truth is, they can AFFECT interest rates, and other economic activity. They can lean one way and they can lean another to try to make the car veer on direction or another. That’s not the same thing is as controlling things. In the absence of the ability to do that, their other main job is to put out propaganda to make people THINK they are Very Smart People Tackling Tough Complex Issues, and use their powers of professional academic research to produce sophistry purporting to prove that their recommended course of action or inaction is correct. One thing I have learned in life is that when dealing with complex systematic problems, academics and experts can become extremely proficient at finding sophisticated ways of avoiding saying, “I don’t know, and no one knows.” In truth, it is the same as with many other endeavors: Everyone is just winging it all the time.
Continue the discussion at the Epsilon Theory Forum...