Why Take a Chance?
February 24, 2015·Money
Back in July, we published what I think is the definitive background piece on Evergrande: Ever Grande.
And we’ve continued talking about the company in the ET Forum ever since: Chinese Credit Tremors.
Today’s ET Pro note is about Evergrande, but it’s not about the company itself or what the likely government response will be (best guess: projects get reassigned and depositors get delayed but made whole, non-management WMP holders are thrown a bone, management WMP holders and shareholders get zeroed-out, and bondholders take a big haircut if they have to take a mark and/or get stuck in a workout facility for a decade if they don’t).
This note is about the market reaction to Evergrande and whether there’s risk of this becoming a systemic problem.
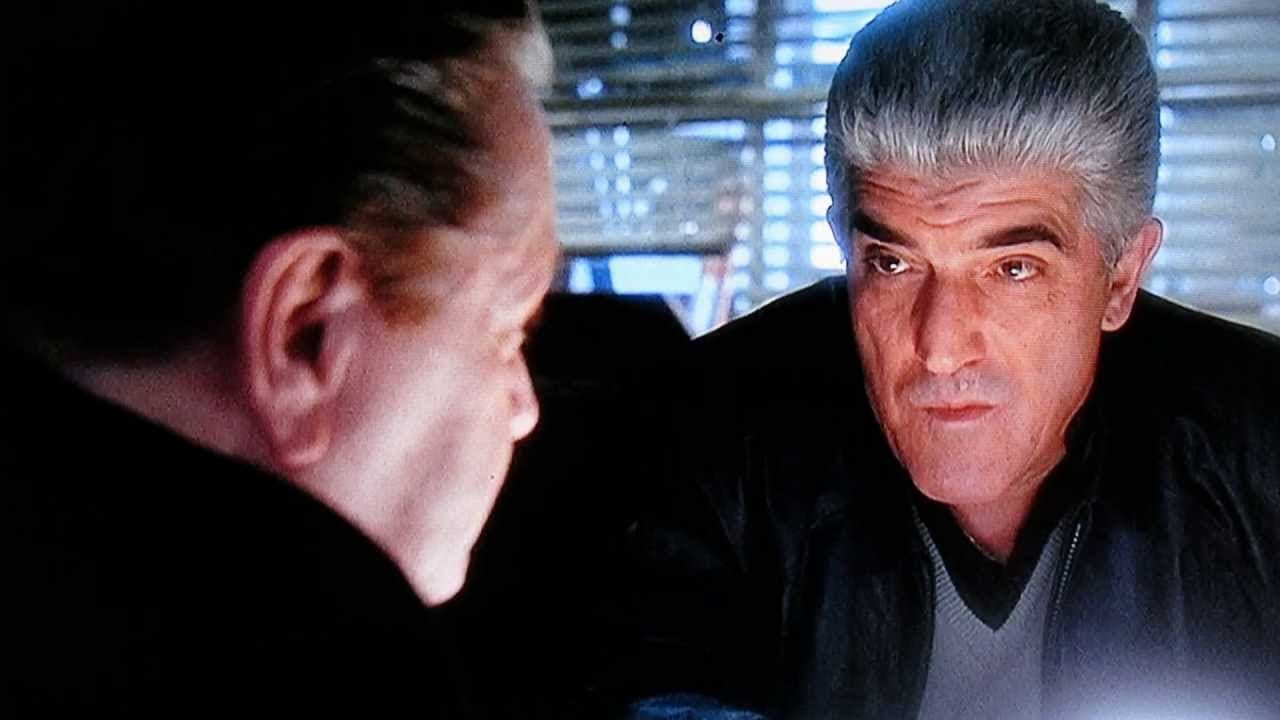
One of my all-time favorite movie scenes is from Casino. The mob capos are all sitting around the table, talking about one of their soldiers who got nabbed by the cops, wondering if he’s going to rat them out. The last one to speak is the Big Boss, Remo Gaggi.
Vinny Forlani: He won’t talk. Stone is a good kid. Stand-up guy, just like his old man. That’s the way I see it.
Vincent Borelli: I agree. He’s solid. An effin’ Marine.
Americo Capelli: He’s okay. He always was. Remo, what do you think?
Remo Gaggi: Look … why take a chance?
And just like that, the decision is made to whack the guy. And anyone associated with the guy. Why take a chance?
It’s one of my favorite scenes because this is exactly the same conversation that takes place in a thousand financial firms, from banks to asset managers to hedge funds to family offices, when a systemically significant company like Evergrande – with more than $350 billion in debt – goes down for the count.
Do you really think that the Chinese government is going to allow Evergrande to be their Lehman moment?
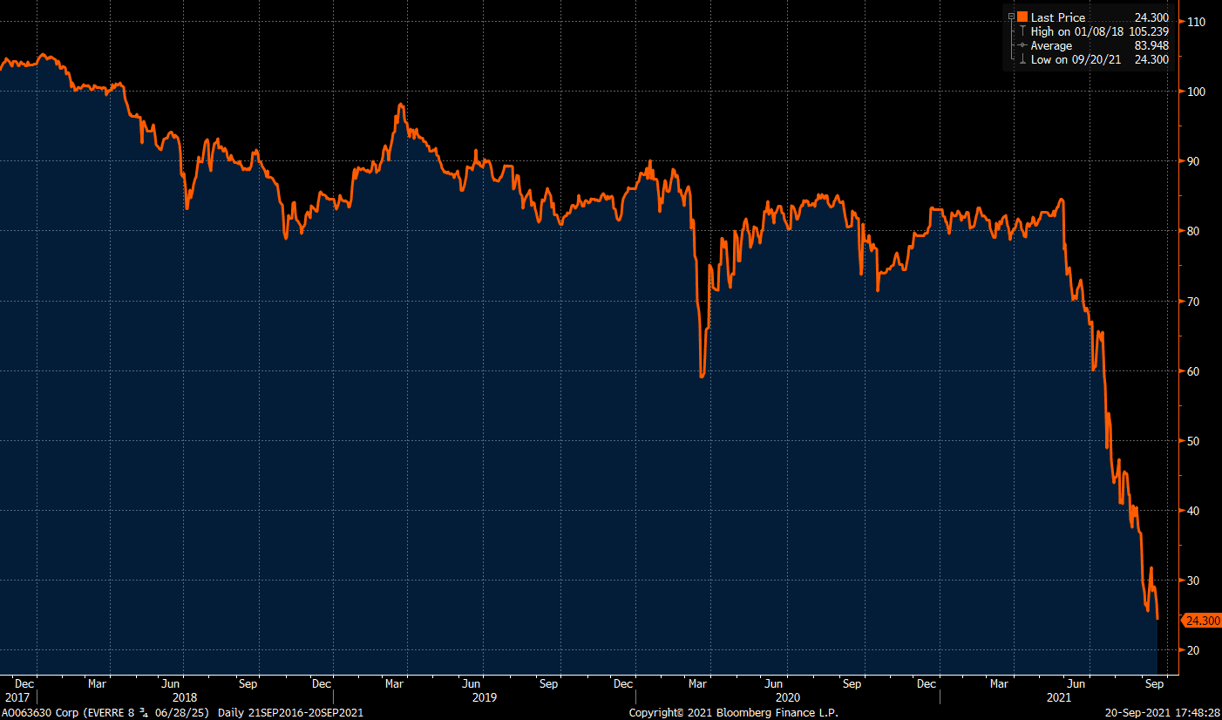
Do you really think that after THREE YEARS of these bonds being under stress (here’s a price chart for a pretty typical dollar-denominated Evergrande bond, which essentially hasn’t traded out of the 80s since the summer of 2018), that any Evergrande counterparty is fatally surprised by what’s going on?
The answer to both of these questions, of course, is a resounding NO.
And yet … why take a chance?
So you sell.
You don’t sell because you “know something”. You don’t sell because you think this is Lehman redux. You sell because you don’t need to be a hero here.
You sell because you can.
And because you can, you sell everything even tangentially related to Evergrande, which for many means anything related to China, certainly anything related to Chinese property, certainly anything related to Chinese equity multiples. For others it means anything related to Asia ex-Japan. For others it means anything related to global trade and global trade finance. For others it means anything related to EM. For others it means anything related to risk assets, period.
For example, here’s the Asia ex-Japan investment grade CDS index. That’s a heck of a spike!
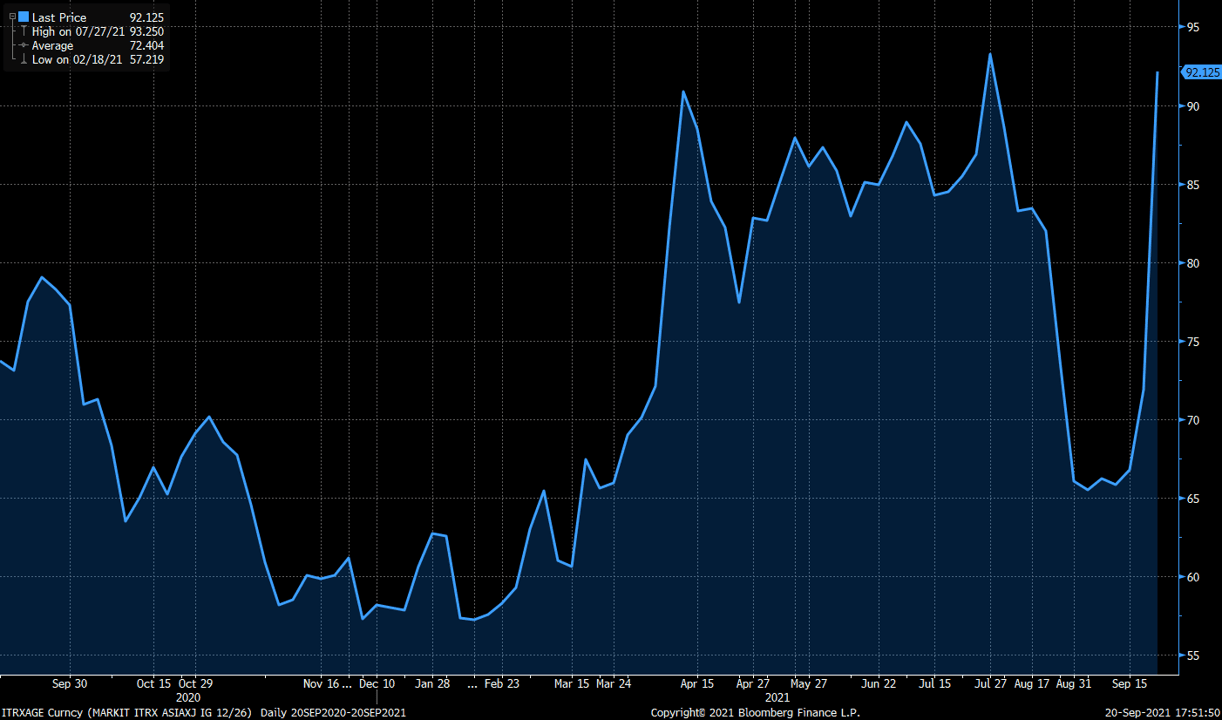
But here’s the same CDS index over a 5-yr period, and suddenly that spike doesn’t look so nasty.
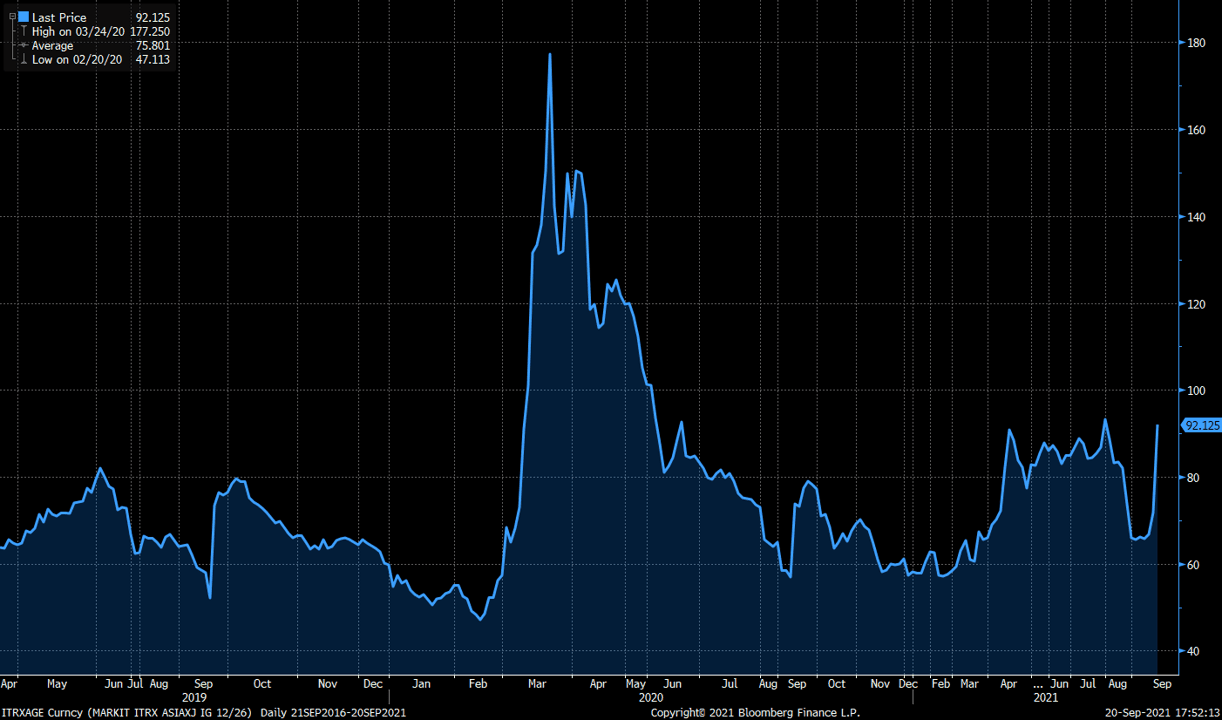
In my experience, the “why take a chance” stage of a well-telegraphed event shock like Evergrande isn’t a one day thing. I’d fully expect the selling to go on for a few days, maybe more depending on the news flow. But it’s also not a forever thing. It lasts until the Chinese government gives an all-clear sign, which honestly is just the absence of an “oh my god, we really don’t know what we’re doing” sign.
The thing to watch from here is not whether or not the market loses confidence in Evergrande. LOL, that ship has sailed.
No, the thing to watch from here is whether or not the market loses confidence in the Chinese government handling of the Evergrande failure.
How do you know if the market loses confidence in the Chinese government? If the Chinese currency gets killed.
Here’s a 5-year chart of USDCNY.
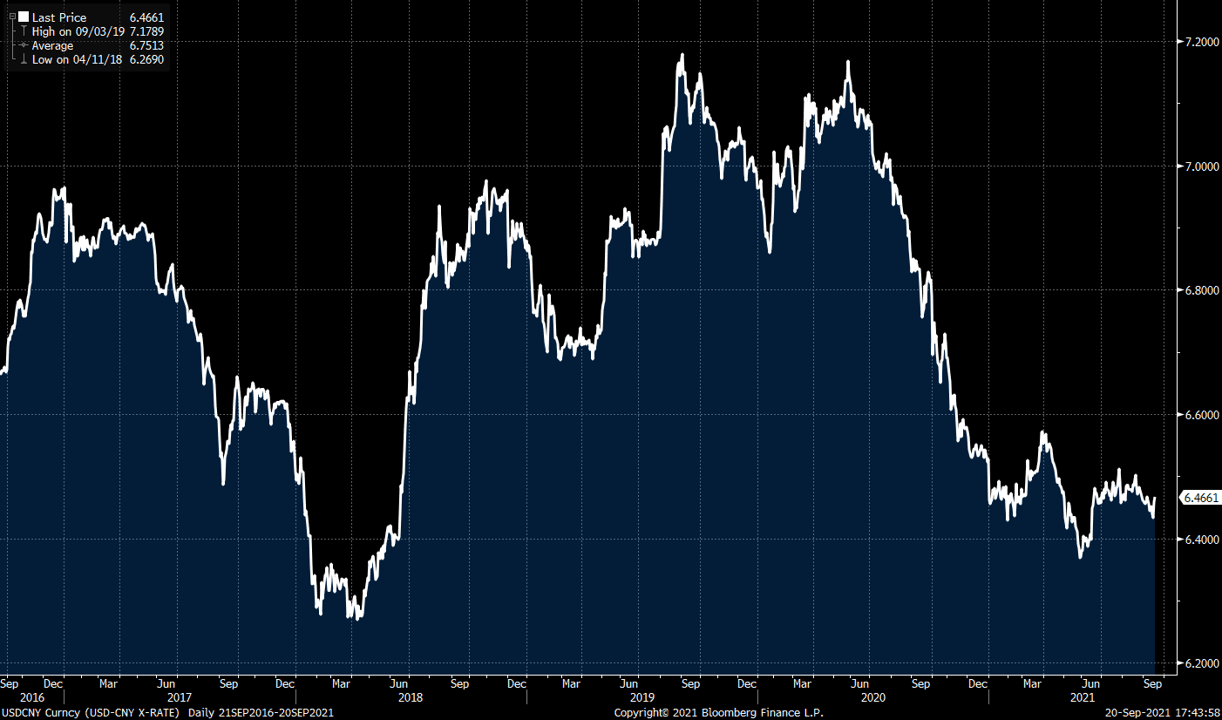
Remember, a weakening of the Chinese currency is a move up in this chart. CNY is staying (very) strong … so far. Up off the three year lows? Sure. Indicative of a lack of confidence in the Chinese government’s reaction to the Evergrande debacle? Not in the least.
Is Evergrande a systemic risk? Is this China’s Lehman moment?
I don’t know. Could be. But unless and until the market loses confidence in China’s response to Evergrande, it’s not a Lehman moment. It can’t be.
So I’m watching USDCNY to see if that changes.
Comments
Start the discussion at the Epsilon Theory Forum...