Locusts' Lament
October 15, 2018·Money
After publishing a few In Brief pieces featuring Quid-based narrative maps, we received a number of emails from subscribers asking us for analysis on other topics.
For those who have read prior notes, you will know that what I usually find most interesting are areas in which otherwise similar topics or words engender very different sentiment and narratives, or in which different universes of authors, commenters and missionaries conjure up different narratives tailored to produce separate responses from distinct audiences. When one long-time reader expressed curiosity about narratives around private equity, I was intrigued. Its results surprised me. But it wasn’t until I checked it against a comparable topic that I found the narrative dimension I really wanted to explore.
First, let’s take a look at the narrative map – as usual, with major cluster names joyfully designated by me with both flippancy and bias – for private equity in 2018.
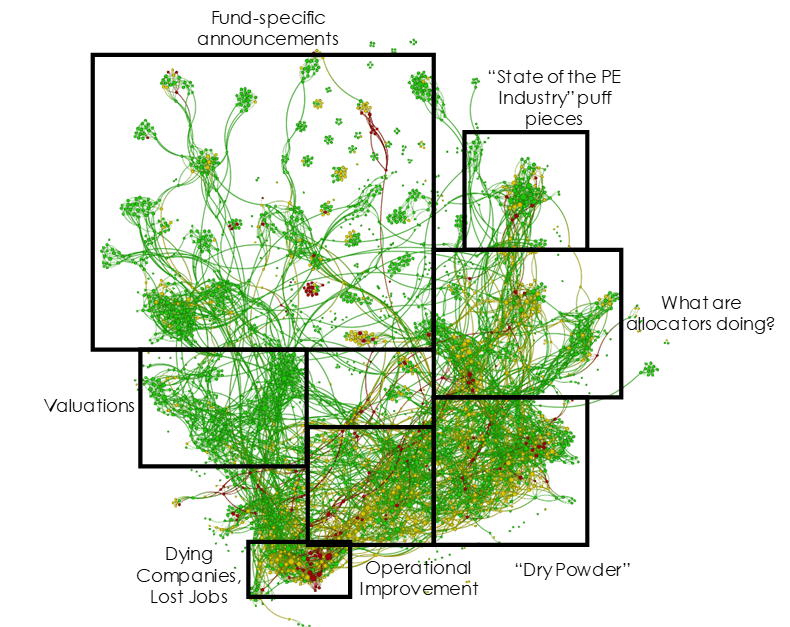
Like the historical treatment of the big tech stocks in media I highlighted last week, media treatment of private equity in 2018 has been glowing. Of the more than 3,100 news stories referencing private equity this year, the positive-to-negative sentiment ratio was nearly 16-to-1. What is more interesting, perhaps, is that a huge number of these stories are using very similar language, terminology and structure. Shown graphically, you see this as the almost non-existent distance between the various clusters. The stories about what allocators are doing are frequently also about dry powder, and frequently also about operational improvements and valuations. In rare cases, they spare a moment to reference the loss of generational businesses, factories, storefronts, high street shopping districts and jobs.
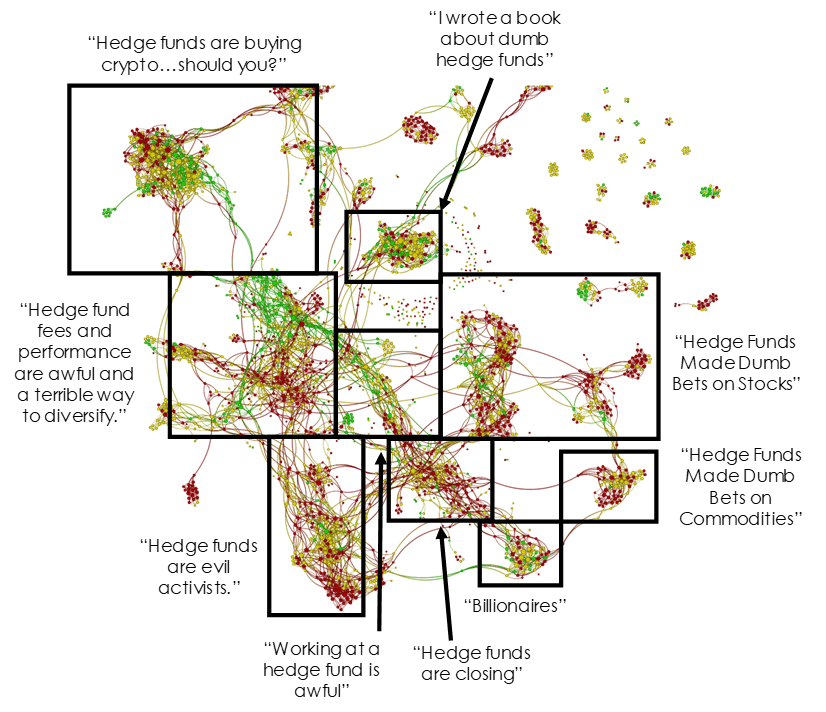
You would be forgiven – especially after the big tech piece – to question whether my priors about the infrequency of this kind of sentiment about financial topics are inaccurate. So let me show you another narrative map. This time? Hedge funds. Same period. Same sources.
Blech.
First, let's talk about the sentiment. Remember how the ratio of positive-to-negative for private equity was nearly 16-to-1? For hedge fund stories, that ratio is about 0.3-to-1. In other words, that's a 3-to-1 ratio in favor of articles written with negative language, terminology and structure. To be clear, some of that is going to be picked up in periods of bad performance just by factually representing that performance. But interestingly for 2018, hedge fund performance has not been especially bad relative to traditional assets or other alternatives. In fact, some hedge funds are having a decent year.
More importantly, the negative sentiment pervades the stories that cover hedge funds on just about every topic. The same glowing discussions of operational improvements by private equity are all about the uncomfortable language of shareholder activism when it comes to hedge funds. Basically the only clusters with non-toxic sentiment are (1) excited discussion of cryptocurrency fund launches and (2) exposés into how difficult it is to get hedge fund jobs.
Fascinatingly, as you see from the relatively distinct clusters, there isn’t a recurring narrative. Nothing that really creates strong links between all these articles, besides the idea that hedge funds are bad. It is simply a topic about which common knowledge is so strong that just about any pot shot will land. There’s no need for any art - just mail it in. Hedge funds are the range pickers at any driving range in America – an irresistible target, and one for which the attacker is unlikely to ever get anything more than the most perfunctory tsking from another golfer.
You won’t find me or Ben arguing that there isn’t truth in some of the stories. We’re on record, for example, opining that the most positively selected trait for hedge fund PM success is probably sociopathy. But the idea that every activist PM is Gordon Gekko and every MD at a buyout shop is Mother Theresa is pure narrative.
Ultimately, however, this is what the lazy, complacent cartoon formed around a view that has been correct for a very long time looks like. Lest we let all this discussion of narratives get in the way of the facts, let’s recall that hedge funds have had a very bad run of performance in almost every category in comparison to nearly any other alternative strategy or traditional asset class. On an absolute and on a risk-adjusted basis. Private equity has performed much better, and because it is usually treated as an either/or with hedge funds by financial and broad media who don’t really understand the very different roles they play in portfolios, some measure of difference in treatment is appropriate.
But there are still some lessons to be gained here:
- Hedge fund managers: Start playing some metagame again, for God’s sake. Aren’t half of you supposed to be WSOP headliners?
- Private equity fund managers: Yes, you’re very smart. Everybody says so. But if you care about the long-term integrity of your franchise and your investments, be especially cautious about believing your own bullshit right now.
- Allocators to alternatives: I would be obsessively focused on finding hedge fund managers with process that has been resilient to the last 10 years, even if it hasn't worked, and on private equity managers with humility and introspection about the sources of their success over the last 10 years.
- Everyone: I would be cautious of consultants or advisers whom you observe painting either strategy with a broad brush today. If someone is pushing private equity to you aggressively as a panacea, or seems to constantly, strangely bring up vague criticisms of hedge funds, you’ve probably found the easy mark the missionaries were looking for. That is usually a good sign that this consultant or adviser is not the guy or gal YOU are looking for.
If you've got other topics you'd like us to examine under this lens, be sure to drop them into the comment section here.