Our True Enemy Has Yet to Reveal Himself
May 5, 2025·Money
THE GODFATHER PART III, Al Pacino, 1990, © Paramount/courtesy Everett Collection, GD3 095, Photo by: Everett Collection (3721)
I don't quote from The Godfather, Part 3 very much because it's not a great movie and isn't even in the same solar system as Part 1 and Part 2. But Al Pacino has two all-time great scenes here: the "pull me back in!" scene after the failed assassination attempt and the final, wordless cut scene of the movie, where -- in a mirror-image contrast to Vito Corleone's heart-attack-while-gardening death scene in Part 1, immersed in green and laughter and love -- Michael collapses and dies alone in a silent, gravelly gray Sicilian courtyard, attended only by a stray dog. Pacino is great throughout the film, honestly, and IMO his realization that the plot against him goes a lot deeper than a blustery Joe Mantegna mobster is better acted than Marlon Brando's far more famous "it was Barzini all along" scene.
Michael Corleone's realization of a deeper problem (as captured perfectly by Silvio's paraphrase in The Sopranos) is summed up in this line -- Our true enemy has yet to reveal himself -- and it's a line I couldn't get out of my head in 2008 and it's a line I can't get out of my head today.
No one remembers this anymore, but in the second half of 2007 auto prices and auto sales rolled over in the United States, as did home prices and home sales -- two classic indicators of an economic slowdown and a recession. The Big Question was whether we were going into a recession or whether this was just a 'mid-cycle slowdown', to use the Wall Street lingo. If you go back and look at the financial media articles and Wall Street analyst reports in Q4 2007, you'll see tons of stuff about that and surprisingly little about the mortgage-backed securities that would actually blow up the world in 2008. I tell people this story all the time, about how 'normal' the Wall Street discourse was in late 2007, and they don't believe me. But if you were there, you know exactly what I'm talking about.
It's not that the true enemy -- an insanely over-financialized US residential mortgage market -- didn't show itself in 2007. Two Bear Stearns credit funds blew up that summer from their exposure to mortgages that were defaulting at an unexpectedly high rate, and the stock price of mortgage originators like Countrywide took a huge hit over the second half of 2007, as did every bank with a mortgage book. But the STORY was that this wasn't a problem for the entire mortgage market and the entire financial system, that it was only a problem for mortgage lending to the poors subprime (low credit score) market. Hell, according to Fed Chair Ben Bernanke throughout 2007, the 'subprime crisis' was not just contained but 'well contained' for any major impact on the broader financial system. Sure, maybe mortgage underwriting standards had gotten a little too lax, especially at 'rogue' companies that took crazy risks like Countrywide and Bear Stearns, but if you just took those two bad apples off the board (Bank of America agreed to buy Countrywide in January 2008, and JP Morgan bought the corpse of Bear Stearns in March 2008), then everything would be fine. "Systemic risk is off the table" was the dominant market story in April and May 2008, and both equity and credit markets absolutely rocked.
It was all a lie, of course, that whole 'well contained' bit about subprime loans, and it wasn't even a particularly well-crafted lie. I remember like yesterday the Countrywide earnings call of August 2007, where the original Orange Man -- tanning bed aficionado and CEO Angelo Mozilo -- told the world that ALL of their mortgages, from subprime through alt-A through prime, were deteriorating at a crazy clip. I mean, it's not like the data was hidden ... every month you could look at the delinquency and default rates for the mortgage securitizations, and every quarter the banks and the originators would take another write down and shuffle their portfolio to avoid taking marks. I remember Countrywide just dumping their Q4 loan data in late January 2008, not even bothering to have a conference call because BofA had announced the acquisition and sidelined Mozilo. Contained to subprime? LOOOL. By Q4 2007 delinquencies and defaults were spreading through every mortgage class and every geography like a highly contagious virus.
The first six months of 2008 were such a psychic struggle for me as an investor. We had gone slightly net short in the hedge fund portfolio in Q4 2007, but the truth is that we went net short more because of a recession view - which was a perfectly comfortable place for my partner and the larger value-oriented firm of which we were part - than because of my 'true enemy' and systemic risk view. We got paid for that net short positioning in both Q4 2007 and Q1 2008, but it was REALLY tough to stay the course in April and May if you weren't prepared to adopt the systemic risk view. From a value investor's perspective, honestly from any normal-times investor's perspective, it sure seemed like a meaningful buying opportunity after the public execution of Bear Stearns and the associated all-clear signs from the Fed at the end of March. We did, in fact, shift from the recession view to the systemic risk view (that's as much a credit to the larger firm and my partner than to me), and in retrospect that was obviously the right call, but man, those months were not easy!
I feel as strongly today as I did in 2008 that our true enemy has not yet revealed himself.
I feel as strongly today as I did in 2008 that the 'normal' market discourse around recession and jobs and inventories acts as a distraction from the systemic risk that is manifesting itself.
I feel as strongly today as I did in 2008 that to the degree systemic risk is being discussed, it is described as 'well-contained' by the US government even though we can all see with our own eyes that it is not contained at all.
I feel as strongly as I did in 2008 that because tens of trillions of dollars and thousands of financial careers are predicated on the systemic risk not happening, it is very hard to 'see' the true enemy and even harder to act proactively to protect yourself. I'll go farther than that. I think that if you're in the belly of the beast it's probably impossible -- and almost certainly it's irrational -- to act proactively on what I'm writing about. Which is maybe the biggest problem that the world has right now, that the people who are most aware of the true enemy to the global economic system find themselves in a position where it is career suicide to do anything about it.
In 2008 the true enemy was the over-financialization of the US residential mortgage market, and the catalyst for the true enemy to wreak havoc in the global financial system was a sharp, universal decline in US home prices.
In 2025 the true enemy is the over-financialization of the US Treasury market, and the catalyst for the true enemy to wreak havoc in the global financial system is a sharp, universal decline in the full faith and credit of the United States.
The imposition of ill-conceived, ridiculously implemented tariffs is one way in which this administration diminishes the full faith and credit of the United States, and over the week of April 7 - 11, we saw a flash crash in both 10-year and 30-year Treasuries following the 'Liberation Day' imposition of tariffs by the US.
Here are the flash crash charts in more familiar interest rate terms (crash in value = spike in rates), with 10-year Treasuries going from 3.90% to a peak of 4.56% and 30-year Treasuries going from 4.33% to a peak of 4.97%. This may not seem like a massive move if you don't follow these markets closely, but I promise you that it is!
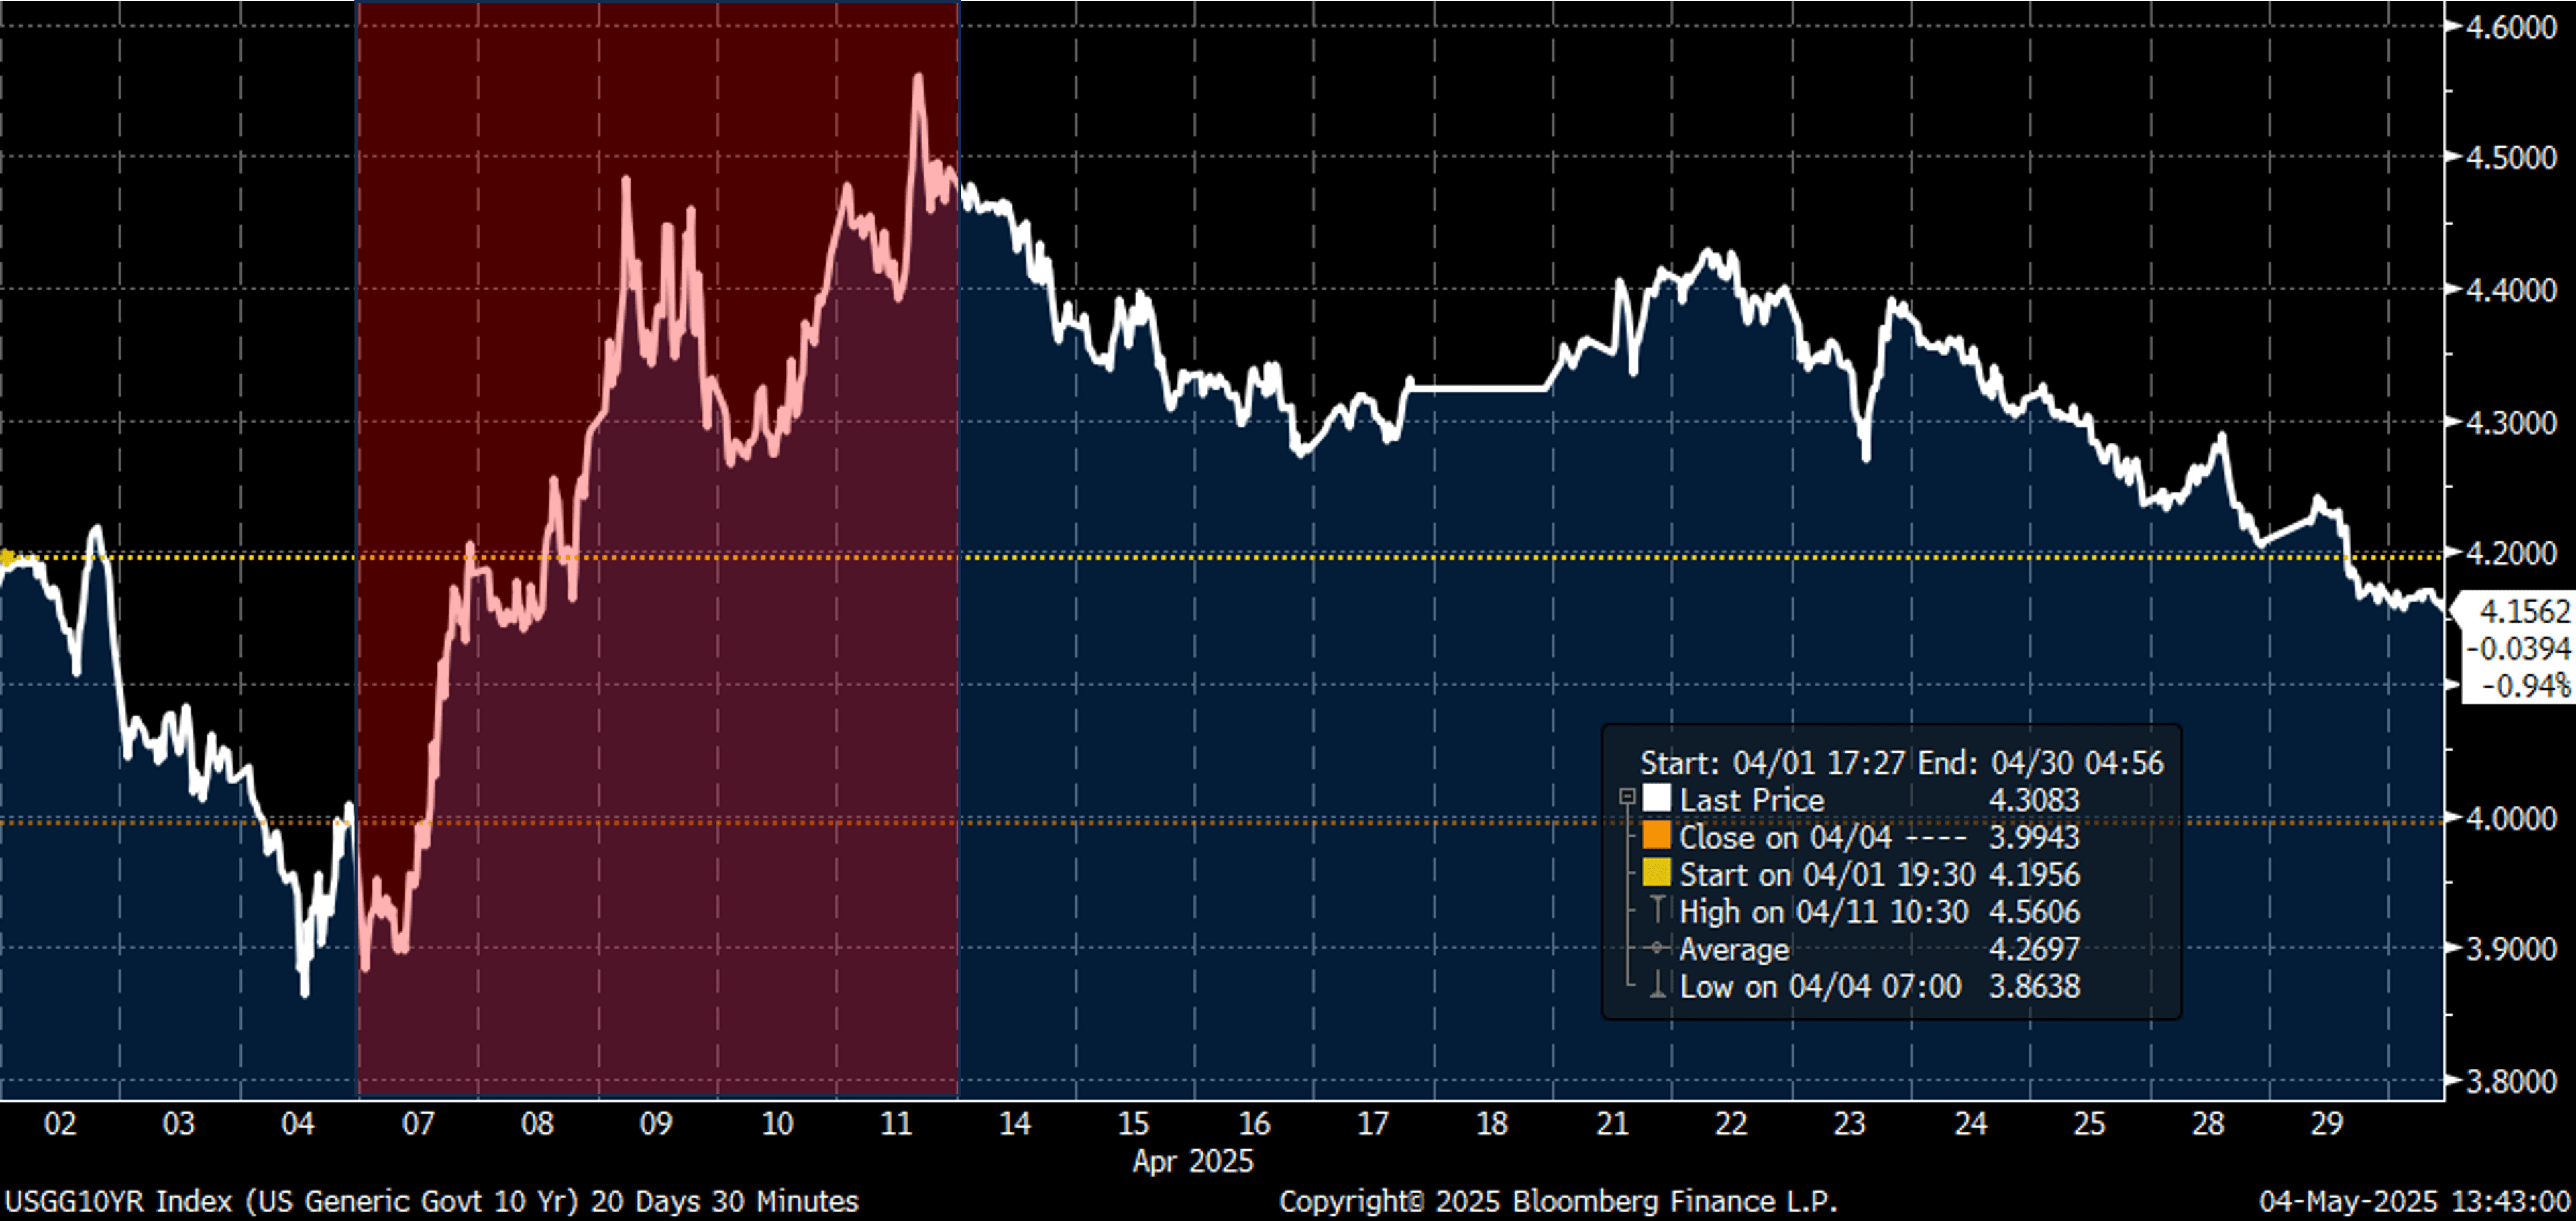
10-year US Treasury rates (Source: Bloomberg Finance LP)
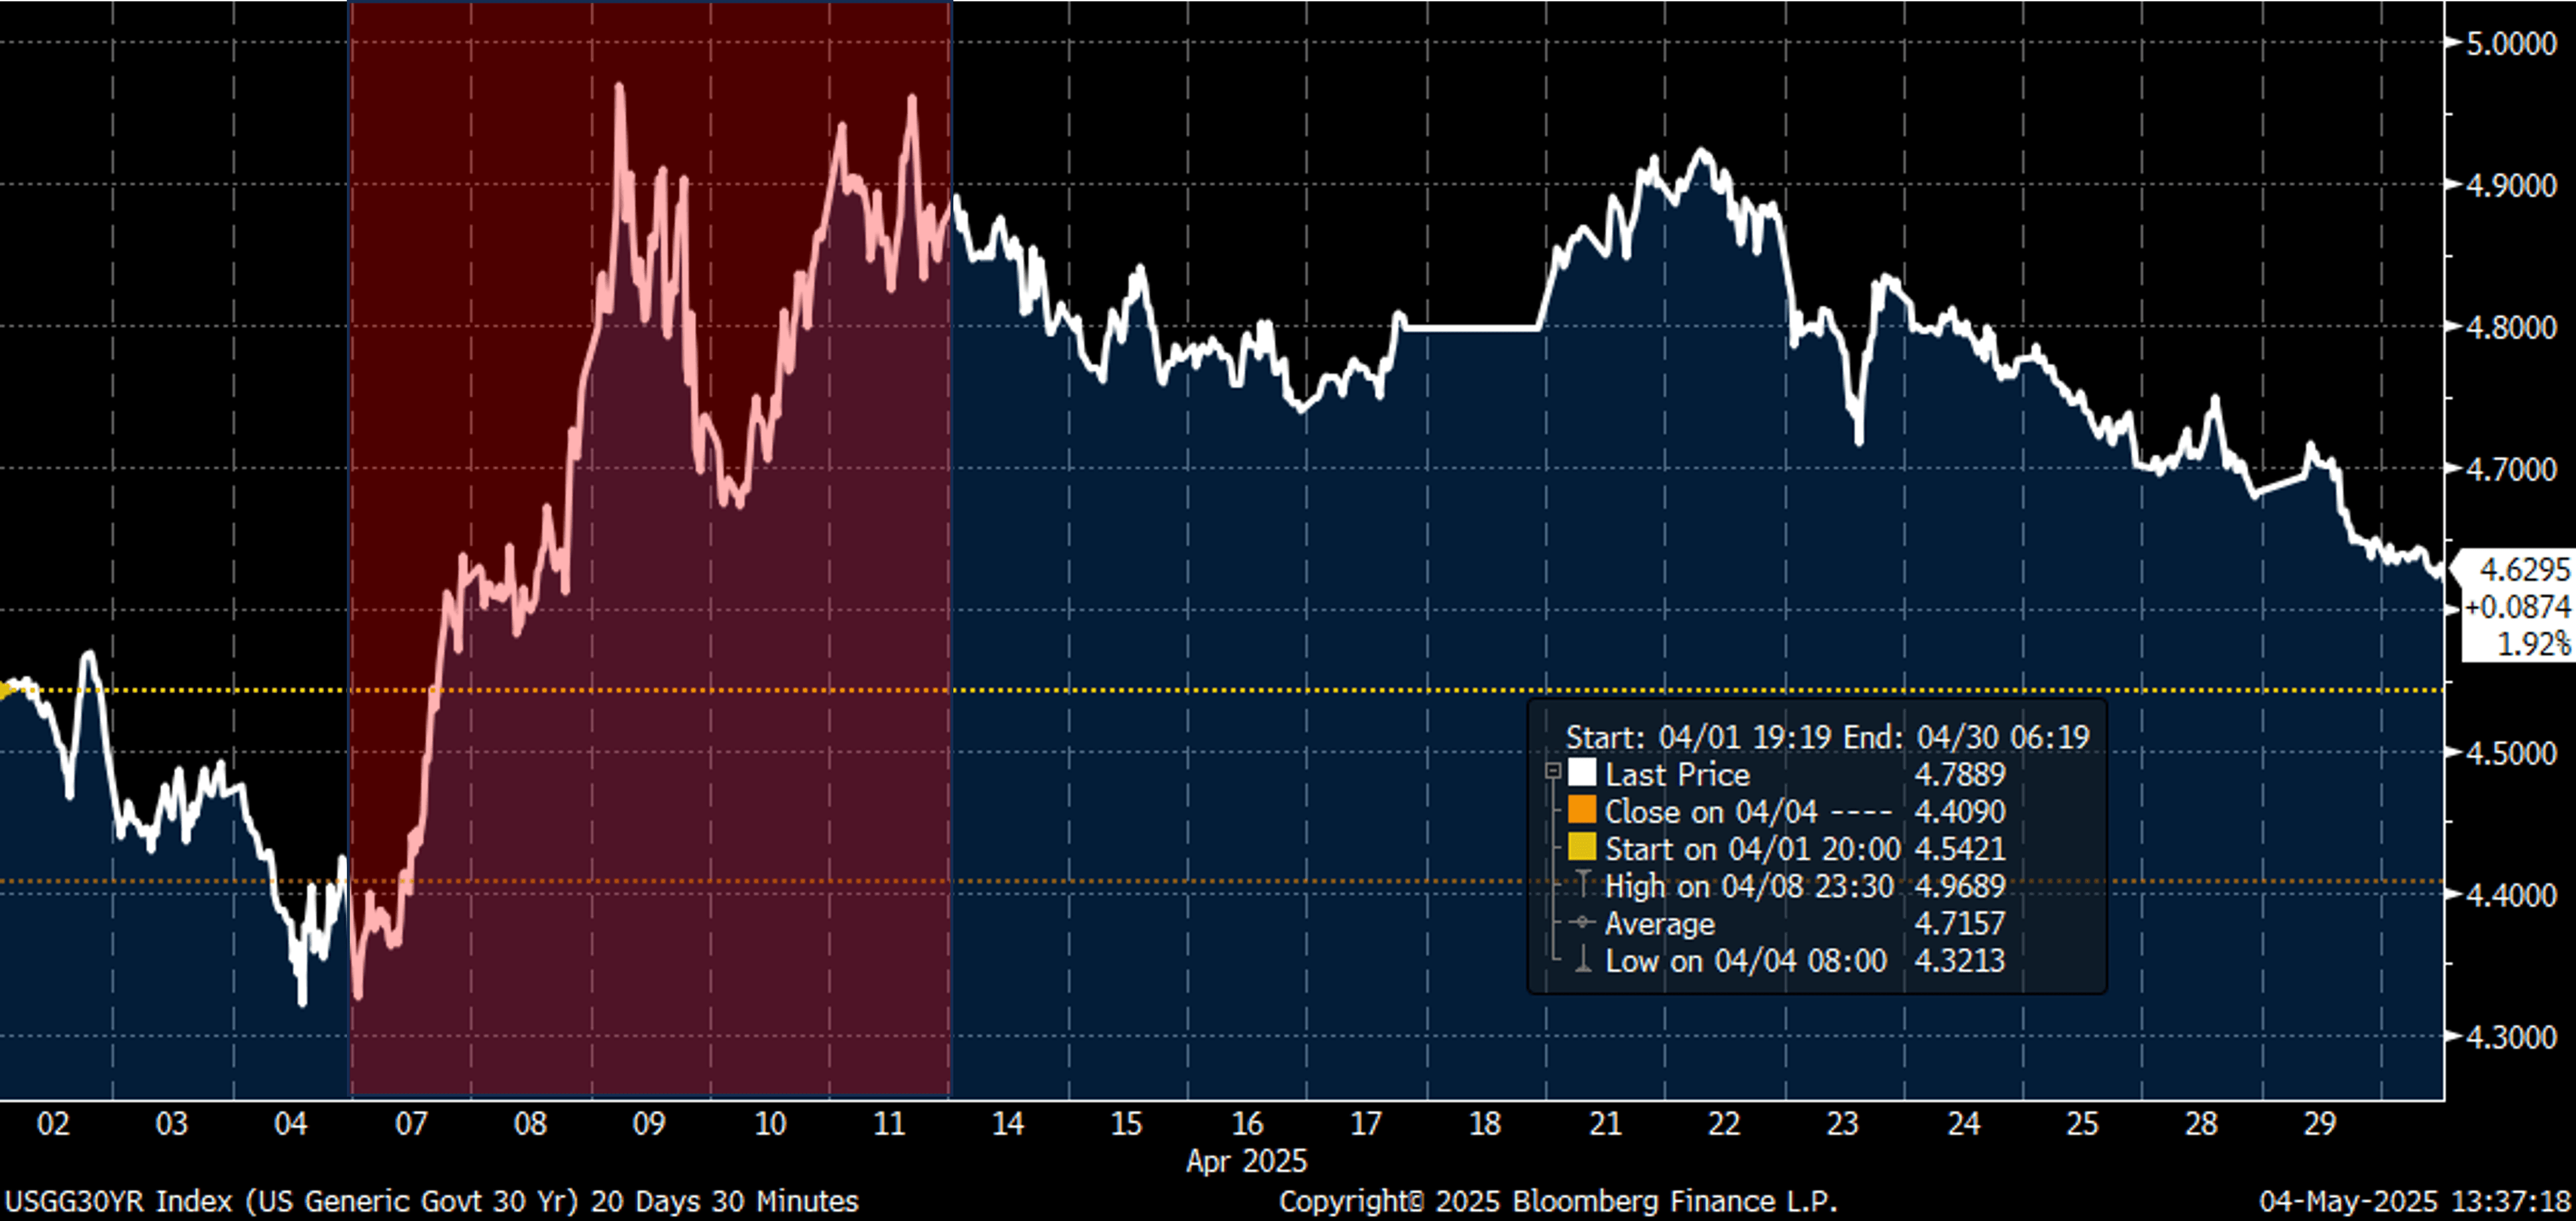
30-year US Treasury rates (Source: Bloomberg Finance LP)
A one-week 65 basis point increase in US long-term interest rates in the face of a dramatic global growth slowdown is an impossible thing. Impossible, that is, if global capital believes that the United States is good for its debts. Impossible, that is, if global capital believes that US debt obligations provide the risk-free rate for the world.
But it wasn't impossible. It happened. The US Treasury market - the touchstone of every loan in the world, every insurance policy in the world, every equity valuation in the world - broke last month, and it broke because the full faith and credit of the United States came into question.
The break was temporary. After the initial Treasury crash on Monday April 7 and Tuesday April 8, the Trump administration rushed to say 'haha! just kidding about those reciprocal tariffs on everyone!' and folded a lot of its cards on Weds April 9. It folded still more of its cards the following week after a resurgent Treasury crash that Friday April 11.
Why did the administration fold most of its tariff cards? Because another one-week 65 basis point increase in US long-term interest rates would break the world. Seriously, everything would break. Every insurer would be in regulatory forbearance and would need to raise capital, and so would most banks. The dollar would crash. Equity markets would crash. Lending and credit would come to a screeching halt. The Fed would be forced to engage in what's called 'yield curve control' where they would flat out buy (and effectively force big US banks to buy) these 10-year and 30-year Treasuries in order to keep their value propped up and their interest rates tamped down. Would that work? Probably. For a while. Maybe. I mean it's not like you're engaging in yield curve control from a position of fiscal and trade strength/surplus like the Bank of Japan buying up all of its long-dated sovereign debt. The Fed would literally be doing the Weimar thing at this point. Which brings me to my next point.
The imposition of ill-conceived, ridiculously implemented tariffs is one way in which this administration diminishes the full faith and credit of the United States. It is by no means the only way.
The classic way to diminish the full faith and credit of your country is to pass a massive, unfunded tax cut and blow out your already obscene budget deficit. Like the 'big, beautiful bill' that the House is taking up this month.
That's the next catalyst for the true enemy to reveal himself.
The craziest part of all this is that we saw just two years ago in the UK what happens to sovereign debt when a government of ideologues true-believers imposes a big unfunded tax cut and blows out their deficit.
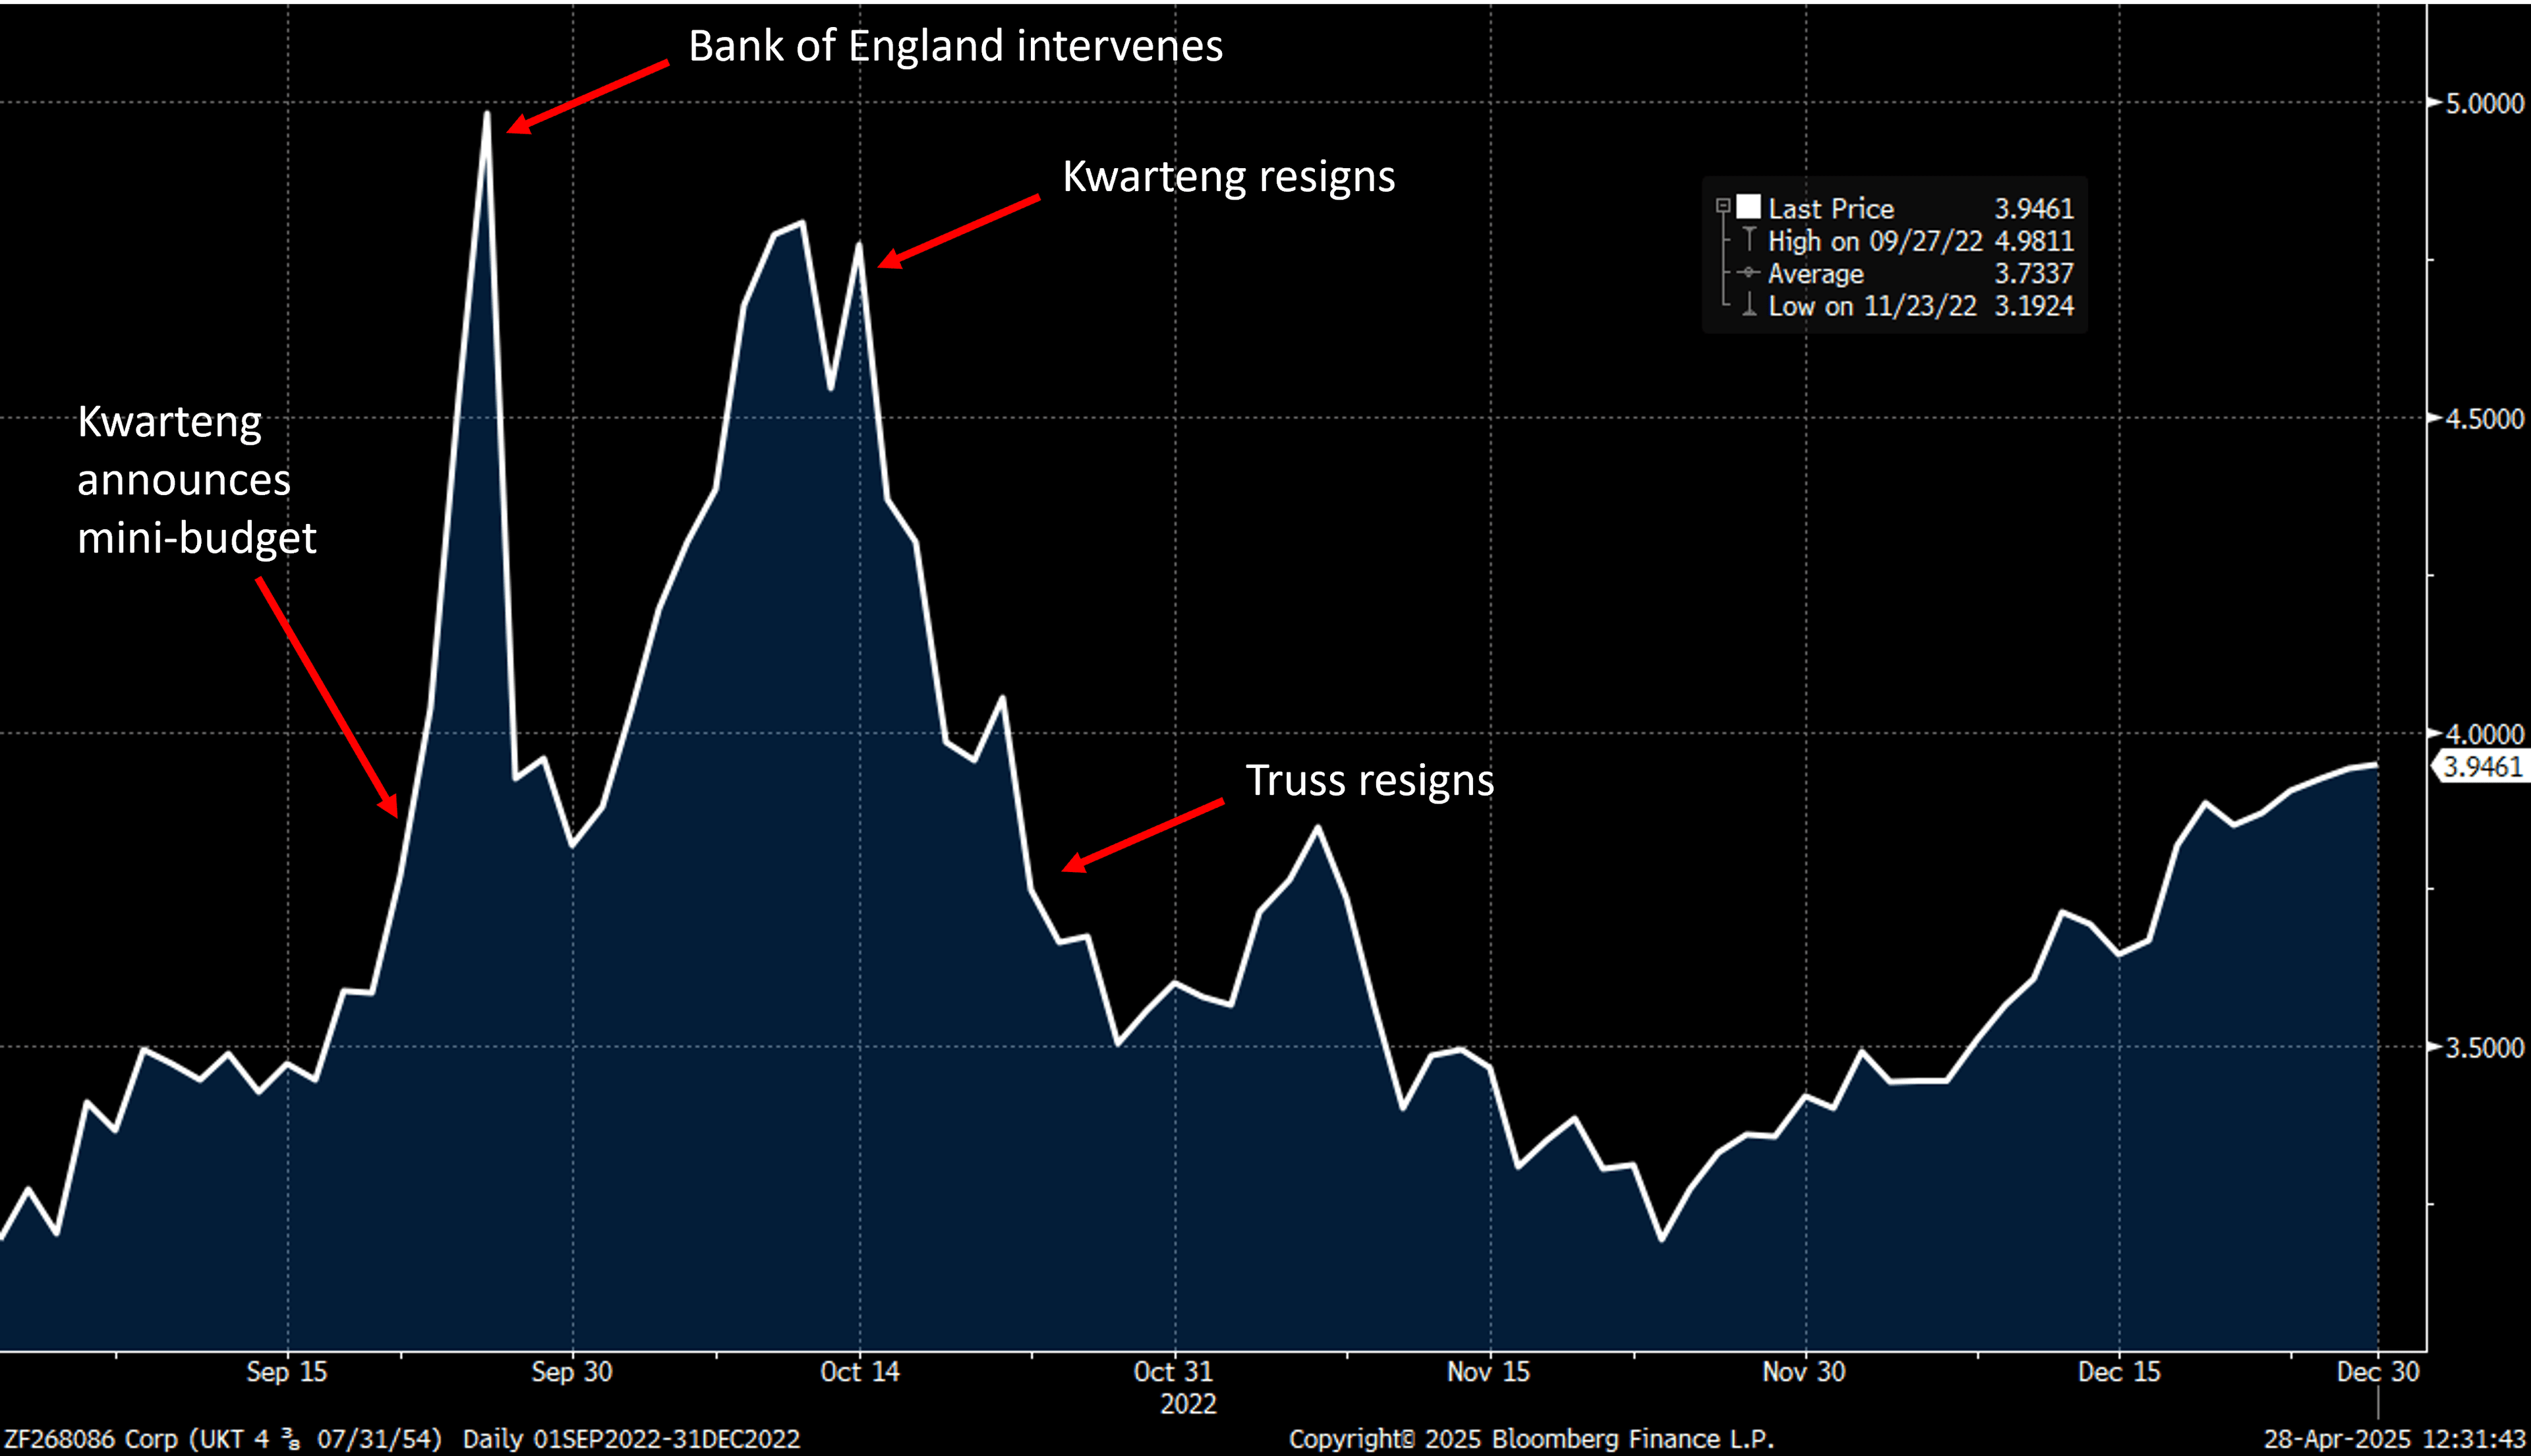
30-year UK Gilt rates (Source: Bloomberg Finance LP)
On September 23, 2022, newly installed Prime Minister Liz Truss and her newly appointed Chancellor (equivalent of our Treasury Secretary) Kwasi Kwarteng presented what was called a 'mini-budget' -- a big new tax cut program that would blow out the budget deficit, but hey, don't worry that we're not funding this by cutting spending or taking in new revenue because all that money going back to 'job creators' will surely spur economic growth and more tax revenue down the road in, like a decade or two. Plus there's gotta be some Waste and FraudTM to eliminate. Sound familiar?
As soon as Kwarteng announced the plan, both the UK pound and their equivalent to 10-year and 30-year Treasuries (called gilts) began to crash (and so rates began to spike). And because some UK pension funds had implemented a too-clever-by-half program to hedge their long-term pension liabilities with long-term gilts, and not only that but had funded the program through leverage and derivatives which could prompt a margin call, and not only that but since they couldn't satisfy the margin call the banks were selling their long-term gilts into this market collapse ... well, in three days the interest rate on 30-year gilts blew out by more than 100 basis points. Now that's a crash!
The Bank of England intervened on Sept 28, pledging to purchase as many 30-year gilts as necessary to stabilize the market and bail out the pension funds over the following two weeks. On the heels of the BOE announcement, rates came quickly back down to where they started by Sept 30, and the crisis was over. Except it wasn't. Yes, the Bank of England had intervened to bail out the pension funds from their disastrous 'liability hedge', but the Truss/Kwarteng policy was still in effect. Long-term interest rates began to climb again in early October, not because the UK pension funds were forced sellers but because global capital had lost trust in the full faith and credit of the UK government. It wasn't until Kwarteng resigned and the unfunded tax-cut plan was removed (with Truss's resignation soon to follow) that the UK currency and sovereign debt returned to some semblance of normalcy.
To be sure, there are plenty of important differences between the UK sovereign debt market and the US Treasury market, all of which make the US market more robust. For example, the US Treasury market is far deeper and more liquid, especially at that 30-year point, and the US debt market has interest-only strips and other instruments that allow pension funds and insurers to hedge long-term liabilities without getting into the same pickle as the UK pension funds. But it's not THAT different, and it's especially not that different in the October market reaction to unfunded tax cuts after the Bank of England bailed out the UK pension funds. No, the main difference I see, and it makes the US less robust to this sort of shock than the UK, is this:
Do you really think that Trump would back down from passing a big, beautiful tax cut bill even if the bond market freaks out about it?
Do you really think that Trump would back down from passing a big, beautiful tax cut bill AND continue to back down from his tariffs?
Or do you think that Trump will start talking about the need to 'do something' about non-US holders of US Treasuries, because they're not 'treating him fairly'?
As someone who has looked at Trump debt offerings for his Atlantic City casinos back in the 2000s, as someone who has listened to Trump absolutely revel in the cramdowns of his former bondholders even as he was seeking new bondholders ... I think we're headed for Door #3. More broadly, I am convinced that Donald Trump sees debt -- whether it's his company's debt or his country's debt -- in purely instrumental terms, as a means to secure some future concession, not as an obligation based on any moral or non-instrumental grounding. And since April 2nd I am convinced that the rest of the world sees that, too.
It's not the tariffs. It's not the tax cuts. It's not the recession. These are just the catalysts, the vehicle through which the true enemy shows himself.
The true enemy is uncompensated risk in the risk-free securities that have been financialized and levered across every substrate of the global economic system, uncompensated risk that comes from a diminishment of the full faith and credit of the United States.
To fight the true enemy we must restore trust in the full faith and credit of the United States.
I don’t know how to do that, especially when the chief executive of the United States is only comfortable when he can act as a BB- credit, but that’s the conversation we will all be having in the weeks and months to come.
Comments
Thanks for writing from the voice of experience. It is hard to put the pieces together without the clarity outlined in this note.
“If you owe the bank $100 that’s your problem. If you owe the bank $100 million, that’s the bank’s problem.”
J. Paul Getty
.
One of the messengers is considered by the markets to be the “adult in the room”, “voice of reason”, or pick your metaphor. Scott Bessent has plenty of bona fides as a markets guy. The issue is that when he speaks now he is carrying the water of a political message, and counting on the credibility earned over the career that predated his public service in the Trump administration. So far, the reception in financial market circles is unblemished. But, I find there is a glib element to his confidence that I cannot shake. It rhymes with Bernanke’s misguided assurance that US housing prices could not fall and that subprime was contained. What else can these operatives say but the script they are given?
Another terrific article. I did not think I could be more bearish long duration UST but this piece did it, Ben! Fun story, in the spring 2007 I was at a Citi MD’s conference in an Orlando resort hotel. The keynote speaker for night 1’s ‘gala dinner’, Tom Maheras, was moved to night 2. As he grabbed the microphone to address the crowd, he apologized for being a day late but assured us that it was in our best interest as “I was busy buying a new mortgage originator - let me rephrase - I was STEALING it!”. A shiver descended my spine. I resigned from Citi 2 months later to join another firm.
One point to add to this gem of a note. During the week of April 7th -11th, at the height of the volatility in the U.S. treasury market, commentary was focused on the possible unwind of the treasury basis trade. That is, the levered trade in which hedge funds attempt to capture the small differences in price between treasury futures and the cheapest-to-deliver treasury bonds underlying those futures contracts. Speculation surrounding the treasury basis trade being the source of bond market volatility was likely based on the Covid experience, when, at the height of that crisis, an unwinding of the basis trade did appear to contribute to treasury market chaos.
But here’s the thing, the data don’t seem to support the thesis that an unwind of the basis trade was a meaningful source of volatility and selling pressure in the treasury market during early April. Might it be a contributor? Certainly. But here’s what I find telling: Wall St. and the White House NEEDED the narrative surrounding the bond market puke to focus on the basis trade. If the source of the selling in U.S. treasuries could be explained by some over-levered clowns, then the problem is contained. Sound familiar? Unwind the basis trades and we all move on. Even more importantly, if the source of the volatility was the basis trade, the Fed has the tools to address the problem relatively easily. Specifically, provide some liquidity and maybe a little coercion to help the market clear. Again, we all move on. BUT, what if the source of the selling and volatility in the U.S. treasury market isn’t offsides positioning among a few levered funds attempting to pick up nickels in front of the steamroller, but structural positioning—amassed over the better part of two decades as foreign buyers accumulated treasury bonds—that needs unwound? Well then, as argued in Ben’s note, the Fed’s gonna need a bigger boat, or bazooka, and it’s called YCC and the implications are nauseating.
Been thinking about Bessent’s Milken Institution speech all day. I have to believe, that nothing gets put in a Treasury Secretary speech accidentally, So when I heard him say “US markets are anti-fragile”, thought that’s an interesting choice of words. Here’s a screenshot of the last paragraph of the speech and link to the full note from this morning:
https://content.govdelivery.com/accounts/USTREAS/bulletins/3defd81
And a screenshot from the description of Nassim Taleb’s book Antifragile. It’s all just very weird, maybe I’m overthinking here…
I do not think you are overthinking this! The Antifragile description also struck me as I listened to the speech and I meant to rewind it to let all of the words used sink in. I also thought it was eerie to quote Buffett about never betting against America the morning after Buffett hung up his cleats and said I’m done! Each of these individually maybe doesn’t move the needle for me, but all of 'em mashed up with unstoppable made the whole thing feel GLIB.
P.S, We should all be tracking Taleb’s Twitter/X account. He is infamous for dressing down those who use his ideas/theories if they contradict his opinion by an inch. So, I did a quick search and…
Ha, that’s pretty funny to see Taleb was on it from right after the speech.
I still wonder if Bessent really believes in tariffs? I believe Trump believes he will win the game of chicken, still not convinced that Bessent does which is the reason he keeps mentioning offramps. He clearly knows markets need to hear that, maybe anti-fragile is rationalizing our tweeter-in-chiefs emotional swings.
Powell has his hands tied, Trump will surely roast him Wednesday afternoon… What does the 10yr do after Powell’s announcement? I don’t know, still feels early to me and that’s always my biggest mistake, putting on the trade way too early.
Excellent article, and some very eerie paralells. Here in Scotland I had just emerged from sitting exams that would allow me to invest for UK clients in early 2008 - baptism by fire.
The article
The article does leave me with some questions. Not criticisms, I’m too confused by everything going on at the moment to provide anything as sophisticated as a criticism… but what is stopping you from seeing what is happening from “simply” being the next phase of “fiscal dominance” ? Trump, volatile as he is, did not singlehandedly create the exploding deficit with its associated record high debt service costs, and demand for USTs/USD has reflected the paradox of fiscal dominance for a while now.
Under fiscal dominance, the easy-peasy solution of higher interest rates to signal credit worthiness is off the table, as is QT. That’s the whole point, under fiscal dominance - monetary policies are subordinate. Which I agree is not good…not good at all, but the US is not the only nation in this pickle.
If Trump manage to kick-start the process of highly-indebted nations’ needing to deal with situation of fiscal dominance in a debt-based monetary system (any number of mental imagery comes to mind, chickens coming home to roost, having to lie in the beds we made etc. etc.) would that not be simple the starting signal for a major global treasury market row of dominos?
Because as Johnson so requently opines, every other nation engaged in debt based monetary systems are currently running not one by two “carry trades” one in their own currency and one in USD. Should the USD weaken, because FX is a zero sum game, each of these other nations will experience their local “carry trade” going against them.
Is this perhaps what Bessent meant by the US being antifragile? Not anti-fragile in the sense that it can avoid the chaos, but in the sense that once the inevitable chaos settles - the US will emerge stronger on a relative basis?
In March 2024, I wrote the following on a different post:
Whether intentional or not, Trump is currently managing to take some attention away from the underlying problem. He might personally believe that he can “fix” everything with his usual playbook of negotiation games, but does any of this really matter? If the destination has been set and all we are doing is arguing about how fast or slow we will get there then it seems time is peerhaps better spent talking about how to protect ourselves from currency debasement?
That is personally my main concern. And I think that the weirdly optimistic equity markets are signalling similar concerns. Why “de-risk” (in a traditional sense), if the solution is just ever more liquidity? In a world where gold and equities are moving upwards in tandem it is the only thing that makes sense to me.
And if this is in fact what will happen then scarcity might again start to mean something.
Em
Continue the discussion at the Epsilon Theory Forum...